By Dr. Tamara Patzer
In brief: Five figures sit behind most tax and estate conversations for owners near the top 1%: the income line, the top bracket, the investment income surtax, the capital gains rate, and the estate exclusion. Each is sourced to the IRS or the Tax Foundation, with a note from a New Orleans tax attorney on why how you own matters as much as what you own.
Tax talk gets abstract fast. Five numbers do most of the work for owners who are near, or already inside, the highest-earning tier. Here they are, with sources, followed by the idea that New Orleans tax and estate attorney Todd M. Villarrubia says ties them together.
What Is The First Number: The Income Line?
About $676,000. For tax year 2023, a filer needed roughly that much adjusted gross income to be in the top 1%, according to the Tax Foundation’s analysis of IRS data1. That group paid about 38.4 percent of federal individual income tax1. It is a snapshot of one year, and it moves.
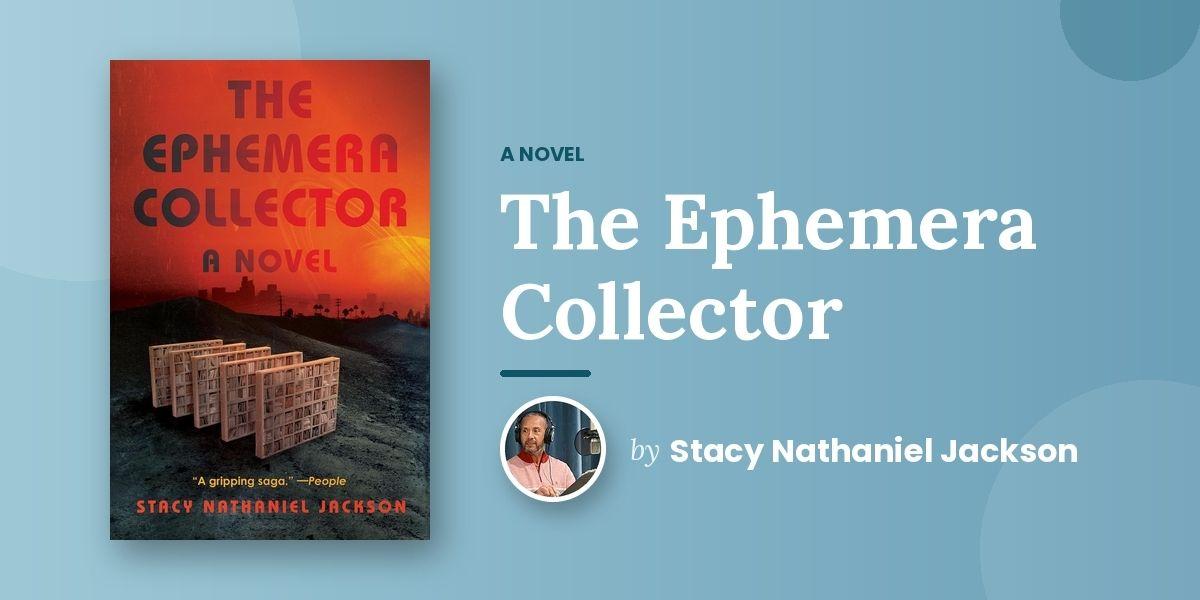
Villarrubia opens his book, Entrepreneurial B.E.A.S.T. Mode™, with the reminder that the line is lower than many believe.
What Is The Second Number: The Top Bracket?
$640,600 for single filers, $768,700 for joint filers. For 2026, the 37 percent federal bracket applies to taxable income above those amounts, according to the IRS2. The IRS page announcing them is marked archival, so confirm current figures before relying on them.
Taxable income is not the same as adjusted gross income, so an owner can sit near the income line and still be below the top bracket, or the reverse. The point is to know both.
What Is The Third Number: The Investment Income Surtax?
3.8 percent. The Net Investment Income Tax applies to certain investment income when modified adjusted gross income is above $200,000 for single filers, $250,000 for joint filers, or $125,000 for married filing separately. Many owners learn about it only when a sale produces a gain on a return that is already large.
What Is The Fourth Number: The Capital Gains Rate?
20 percent. Long-term capital gains are taxed at 0, 15, or 20 percent, and an asset must be held for more than one year to qualify as long-term. For 2025, the 20 percent rate applied above $533,400 of taxable income for single filers and above $600,050 for joint filers. The IRS page gives no 2026 thresholds, so check the current year before planning a sale. The same page notes higher maximum rates of 28 percent for certain items, including collectibles and the taxable part of qualified small business stock.
What Is The Fifth Number: The Estate Exclusion?
$15,000,000. That is the 2026 federal basic exclusion amount per person, as the IRS lists it5. An owner whose company, real estate, and investments together pass that amount has a federal estate tax question unless the plan changes the answer.
What Do The Five Numbers Have In Common?
They all depend on how things are held, not only on what is owned. Villarrubia states the idea in two lines. The first is “Wealth preservation depends not on what you own, but on how you own it.” The second is “Structure is not merely an accessory to success; it is essential for its long-term survival.”
In his book, the point comes from the chapter on business structure. Different entities can be taxed differently depending on the elections filed with the IRS, and which one fits depends on the owner’s situation. An owner who knows the five numbers but has never asked how the assets are titled has only half of the picture.
He is just as direct about what goes wrong when nothing is done: “Wealth doesn’t fail because of taxes; it fails because of disorder.” In his telling, the numbers matter less than whether someone has put the pieces in order before they are needed.
Which Of The Five Usually Surprises Owners Most?
It tends to be the third, because it is not a bracket and does not show up on the tax tables most people look at. It is a separate tax with its own thresholds, and it sits on top of everything else. The estate exclusion is a close second. An owner with a $40 million company can feel modestly off because cash is tight, and still hold an estate well above $15,000,000. Both surprises come from the same cause: the balance sheet is mostly one illiquid asset.
A short exercise helps. Take the number you expect to pay on a sale and compare it with the cash you could actually raise without selling anything. If the second figure is far smaller, the owner has a liquidity gap, and closing it is a planning task that takes time.
How Can An Owner Use This List?
Write the five numbers on a single page and put your own next to each one: last year’s adjusted gross income, taxable income, investment income, any gain you expect from a sale, and your estimated estate. The gaps and surprises on that page are the agenda for a meeting with a licensed attorney and a tax professional.
How Should A Reader Keep These Numbers In Perspective?
As context, not as targets. Figures like these describe the country, and they are updated as new data arrives. The useful move is to ask what each one implies for your own household: a threshold you might cross in a sale year, a limit that could shape an estate, a rate that applies to a gain. Write down the one that matters most to you and bring it to your next meeting with your attorney and tax professional.
Common Questions
Do These Numbers Change?
Yes. Thresholds are adjusted regularly, and Congress can change rates and exclusions. Each figure above carries its year.
Are These State Numbers?
No. They are federal. State income tax and state estate rules can differ and are not covered here.
Is Crossing The Income Line A Problem?
No. It is information. It means a larger share of the planning questions applies to you.
Why Does The List Start With Income And End With Estates?
Because that is the order in which most owners meet them. Income comes first, a sale brings the gains and the surtax, and the estate exclusion arrives last, usually after the owner has stopped thinking about it. Planning tends to work better when the order is reversed and the end is considered first.
Sources
- Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023
- Internal Revenue Service, Tax inflation adjustments for tax year 2026
- Internal Revenue Service, Topic no. 559, Net Investment Income Tax
- Internal Revenue Service, Topic no. 409, Capital Gains and Losses
- Internal Revenue Service, What’s New: Estate and Gift Tax
About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.
About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; Website: Wealth Planning Law Group
Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.