Thursday, August 6
Business · Technology · Leadership

Working Capital for Seasonal Businesses: How to Fund the Slow Months

Every seasonal business knows the pattern. A landscaper is flat out from April to October and quiet through the winter. A beach town restaurant earns most of its year in twelve summer weeks. A retailer depends on the holiday rush. Revenue arrives in waves, but rent, payroll, insurance and loan payments arrive every month.

Working capital can bridge that gap, but only if it is structured around the seasons rather than against them. This article explains how seasonal businesses can plan their cash flow, which funding options fit an uneven year, and how to find qualified lenders and reputable brokers who understand seasonal revenue.

Why seasonality makes funding harder

Most funders underwrite on recent bank statements, usually the last three to six months. For a seasonal business, those months can tell very different stories depending on when you apply. Apply in August and your deposits look strong. Apply in February and the same business can look like it is struggling.

That timing affects everything: the amount you qualify for, the cost, and the size of the payment the funder expects you to carry. It also creates a trap. Owners often seek funding in the slow season, when they need it most and look weakest on paper, and end up accepting expensive terms with payments sized for revenue they will not see again for months.

Understanding this dynamic is the first step toward avoiding it.

Start with a twelve-month cash flow map

Before you approach any funder, build a simple month-by-month picture of your year. You do not need accounting software. A spreadsheet with three rows is enough:

  1. Expected deposits for each month, based on the last two or three years.
  2. Fixed costs that do not change with sales: rent, insurance, base payroll, equipment payments, software and existing debt.
  3. Variable costs that rise and fall with business: inventory, seasonal staff, fuel and materials.

Subtract costs from deposits for each month and you will see exactly where the gaps fall, how deep they are, and how long they last. That map tells you three things every funding decision depends on: how much you really need, when you need it, and when you can comfortably repay it.

Many owners discover that they need less than they feared, or that the gap is shorter than it felt. Others discover that they need funding earlier than planned, to buy inventory or hire staff before the busy season starts.

Funding options that fit an uneven year

Not every working capital product suits a seasonal business. The best fits share one feature: repayment that bends with revenue or that can be timed to the busy months.

Business lines of credit. A line of credit is often the best tool for seasonality. You draw only what you need during the slow months, repay when revenue returns, and pay interest only on the balance you use. Apply for a line during your strong season, when your statements look their best, so it is ready before you need it.

Revenue-based financing. Repayment is a fixed percentage of revenue rather than a fixed amount. Payments fall automatically when sales fall, which protects cash flow in the off-season. The trade-off is a higher total cost than a bank line.

Working capital advances with reconciliation. Many working capital advances are repaid by fixed daily or weekly debits, which can hurt in the slow months. Look for agreements with a clear reconciliation clause that lets you request lower payments when revenue drops, and ask how quickly the funder responds to those requests. Weekly payments are usually easier to manage than daily ones.

Equipment financing. If your seasonal need is equipment, such as a new mower fleet, a food truck or a snow plow, financing the asset directly usually costs less than using general working capital and spreads payments over the asset’s useful life.

Inventory financing. Retailers preparing for a holiday rush can sometimes borrow against the inventory itself, repaying as it sells.

SBA loans. For established seasonal businesses with good records, an SBA working capital loan offers the lowest cost and longest terms. It takes longer to arrange, so plan months ahead.

Build a reserve in the busy season

Funding is only one tool. The cheapest working capital a seasonal business will ever use is its own. Setting aside a fixed share of every busy-season deposit, even five or ten percent, builds a cushion that shrinks or eliminates the off-season gap. A reserve also strengthens your bank statements, because a healthy average daily balance is one of the things underwriters value most.

Timing your application

The single most useful tactic for seasonal businesses is to apply before you need the money. Funders see your strongest months, offer better terms, and you avoid making decisions under pressure. A line of credit opened in September costs nothing until you draw on it in January.

If you must apply in the slow season, give your broker or funder context. Provide statements from the same months in prior years so they can see the pattern, and a summary of your busy-season revenue. A reputable broker will present your file in a way that shows the full year, not just the quiet stretch.

Sizing payments around your seasons

Ask every funder for the payment amount and frequency in writing, then test it against your slowest month, not your average. A daily debit that is easy in July can drain the account in January. If the payment does not work in your weakest month, the deal does not work.

Ask specifically:

  • Can payments be weekly instead of daily?
  • How does the reconciliation process work, and what documents do I need?
  • Is there a discount for paying early once the busy season arrives?
  • Will the funder consider a structure with lower payments in the off-season?

A funder that answers these questions clearly is worth more than one offering a slightly lower rate with rigid daily debits.

Avoid the slow-season stacking trap

The most damaging pattern for seasonal businesses is stacking: taking a second or third advance in the off-season to cover the payments on the first. Each new position adds its own debit, and by the time the busy season returns, much of its revenue is already committed to repayment. Some businesses never catch up.

If you are already carrying an advance and the slow season is squeezing you, talk to your existing funder about reconciliation before adding another position. A reverse consolidation, which lowers your combined daily payment over a longer term, may also help, although it increases the total cost.

Finding funders who understand seasonal revenue

Some funders are comfortable with seasonal deposits. Others decline anything that dips. Sending your file to the wrong ones wastes time and adds credit inquiries.

MCA Directory helps brokers match businesses to funders whose published criteria fit, including minimum revenue, payment frequency, maximum term and industry. Its industry pages group funders that actively work with sectors like construction, farming, retail, restaurants and transport, many of which are seasonal by nature. Verified funders are hand-vetted and confirmed to be actively funding, and brokers review funders on underwriting honesty and merchant treatment, which matters when you need a funder that will actually honor a reconciliation request.

Before you commit to a broker, check their record. The FundedUSA Instagram page posts confirmations of businesses funded through reliable lenders and brokers, so you can look for funded businesses in your industry and see who is actually closing deals.

How funders and brokers join the platform

Funders that want brokers to find them can apply through the verified funder listing page, which sets out the listing criteria, placement options and the vetting behind the verified badge. Brokers can set up access through the broker marketplace, where CRMs, lead providers, legal services and other tools are organized by category.

Watch for off-season scams

Fraudsters know when seasonal businesses are most desperate. Unsolicited offers spike in the quiet months, often promising fast approval regardless of your statements. Remember one rule: no legitimate working capital provider requires you to send money before you have a signed agreement and the funds are in your account. A request for a deposit, insurance payment or release fee before funding is a scam.

MCA Directory publishes a clear guide to these warning signs and offers a private fraud reporting form. Reports go only to its team, are never forwarded to the company named, and help the industry spot schemes before they reach the next owner.

The bottom line

Seasonality is predictable, which means it can be planned for. Map your year, apply in your strong season, choose repayment that bends with revenue, size payments to your slowest month, and avoid stacking to cover a temporary dip. With the right structure and the right funding partner, the slow months become a manageable part of the business rather than a crisis.

Disclaimer: This article is for general information only and is not legal, tax or financial advice. Working capital costs, terms and eligibility vary by funder and by business. Review any agreement carefully and consult a qualified professional before signing.
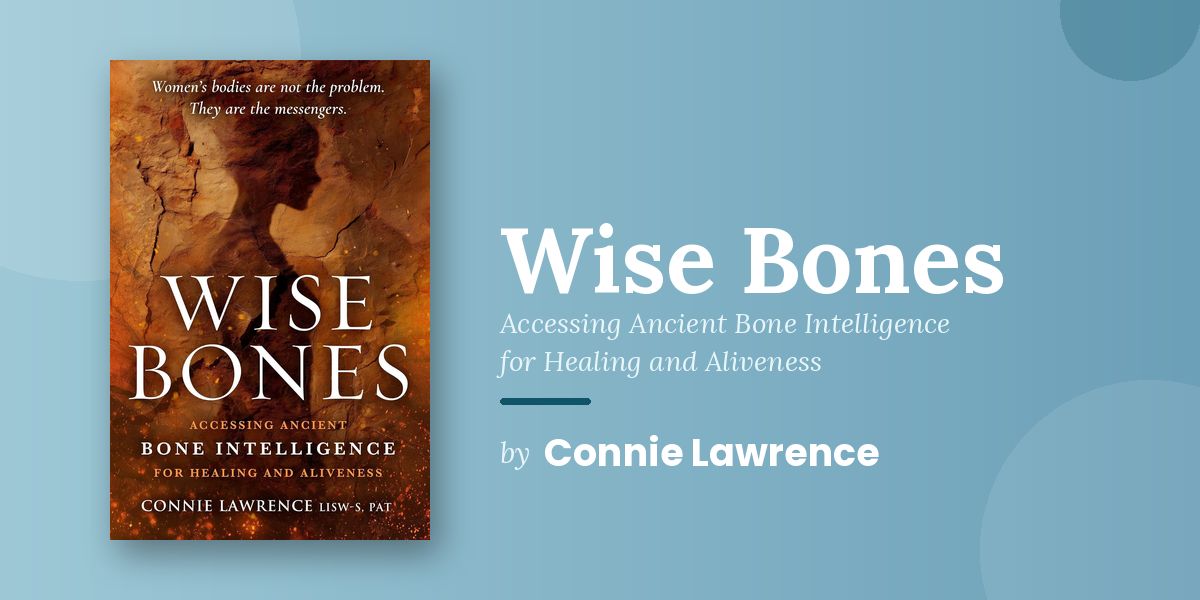
A World in Trouble Needs the Wisdom of the Bones, and Connie Lawrence Spent Twenty Years Finding Her Way Back to It Before She Could Write the Book That Guides Others Home

By: Mauren Mackenzie

There is a quality in Wise Bones that is unusual in healing literature and that accounts for much of what makes it genuinely compelling rather than simply interesting: the quality of genuine necessity. Connie Lawrence is not writing about accessing ancient bone intelligence as a self-improvement strategy or a wellness optimization technique. She is writing about it as something urgently needed, as a resource that the modern world has specifically suppressed and that individuals and societies are paying a high cost for losing. The call to awaken the wisdom of our bones with which the book closes is not a gentle invitation to a pleasant new practice. It is a call to remember something essential that the dominant culture has worked systematically to make us forget.

Lawrence arrived at this understanding through more than twenty years of practice as a trauma therapist, from the inside of the conventional framework rather than from the comfortable distance of its critics. She spent those years working with calming and soothing, the go-to approaches of both clinical therapy and the self-help world, and she arrived at the understanding not through theoretical dissatisfaction but through the specific and growing recognition that these approaches, while genuinely valuable, were systematically bypassing a dimension of intelligence that lived deeper in the body than they were designed to reach. The journey she traces from a wistful romance to finding a backbone and eventually to the discovery of bone intelligence as both a personal and professional framework is honest in the specific way that only direct experience can produce.

The framework she has developed, part of the leading-edge science of somatic transformation, is built around the connection between the intelligence she is describing and its evolutionary origins. The bones are not simply structural. They are historical, carrying in their molecular memory the accumulated wisdom of millions of years of adaptation and survival. The modern world’s systematic prioritization of cognitive knowing over embodied knowing has made that memory inaccessible rather than absent, and reconnecting with it is not a matter of learning something new but of remembering something ancient that was always there.

Lawrence writes with the storytelling quality and the body-based reflections that give the book both intellectual range and embodied accessibility, moving between anthropology and personal narrative and clinical insight in a way that reflects the integration she is advocating for rather than the fragmentation that the conventional approach tends to produce. Wise Bones is both a challenge to traditional therapeutic mythology and a genuine contribution to the science of somatic transformation, offered with the authority of someone who has spent twenty years earning the right to make it.

If you are ready to go below the level of calming and soothing and reconnect with the ancient evolutionary intelligence that the modern world taught you to forget, Wise Bones by Connie Lawrence is the book that makes that reconnection both intellectually grounded and genuinely experiential. Pick up your copy on Amazon today and begin the return to the grounded wisdom and aliveness that your bones have always carried.

Disclaimer: This article is provided for general informational and educational purposes only and is not intended to constitute medical, mental health, psychological, therapeutic, or other healthcare advice. The concepts, perspectives, and approaches discussed are presented for informational purposes and should not be considered a substitute for evaluation, diagnosis, treatment, or guidance from a qualified healthcare or mental health professional. Individual experiences and responses to therapeutic or wellness practices may vary. Readers should consult an appropriately licensed professional regarding any health, mental health, trauma-related, or other personal concerns before making changes to their care or treatment. References to research, therapeutic approaches, books, authors, or wellness practices do not constitute an endorsement or guarantee of their effectiveness or suitability for any individual.

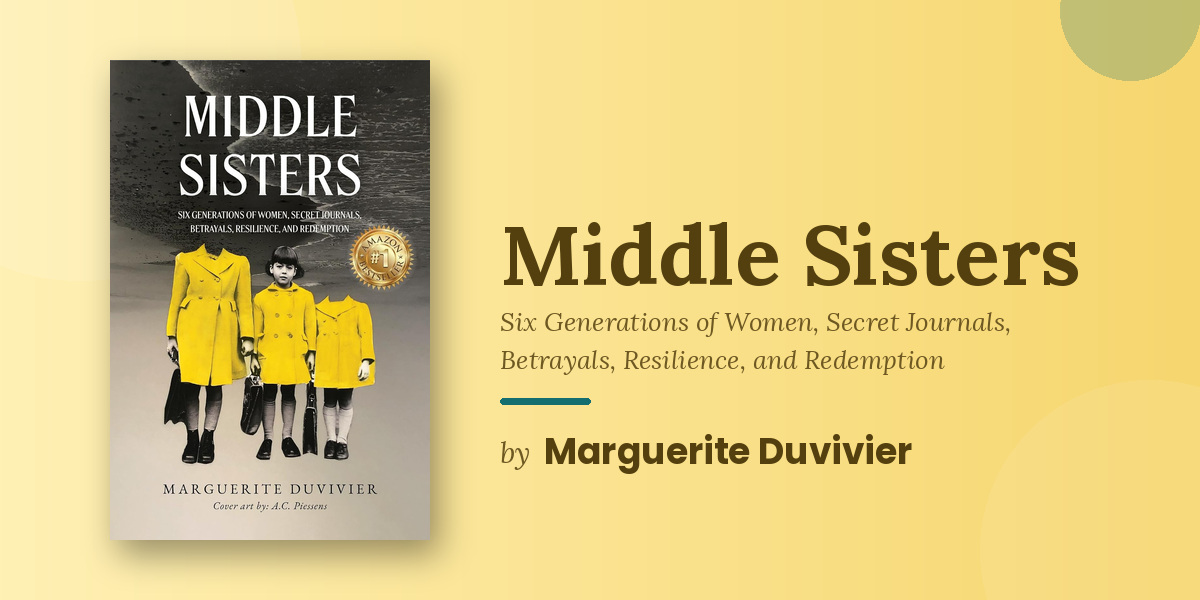
Middle Sisters Traces a Family’s Story Through Two World Wars and Generations of Change

By: Kristine Kennedy

The women whose stories fill Middle Sisters were not the kind of women who made official history. They were the kind whose lives happened in the spaces between official history, shaped by the wars and the economics and the social structures that surrounded them without ever fully controlling them, and who left their own record not in archives or newspapers but in secret journals discovered posthumously, in the memories of children who were watching even when they were not supposed to understand what they saw, and in the patterns of behavior that repeated and occasionally broke across six generations. Marguerite Duvivier, writing under a pseudonym, is the Associate Professor in Anatomic Pathology who examined all of this evidence and wrote the memoir that finally gives these women the honest account they were never going to receive from any other source.

The saga begins in Belgium in 1908 with Lydie, the dominant mother whose decision to coerce her middle daughter Zilda into a loveless marriage with a greedy and self-serving man sets in motion a pattern that the memoir traces with unflinching specificity across the generations that follow. The coercion is not abstract. It is a specific act in specific circumstances by a specific woman whose own relationship to power and to her daughters is rendered with the complexity that makes her comprehensible even when she is not forgivable.

Zilda, the middle daughter who becomes the memoir’s first sustained focus, spent her life in the loveless marriage her mother arranged and kept her private record of it in journals that she never intended anyone to read. The posthumous discovery of those journals is the archival event that makes the memoir possible in its most intimate and most specific form, providing documentary evidence of an interior life that the official version of Zilda’s existence never acknowledged. Her own middle daughter Marguerite, fiercely independent and determined to chart a different course, married a brilliant and unfaithful man whose gifts and flaws exist in genuine proportion and whose relationship with Marguerite is rendered without the simplification that would make him easier to dismiss.

Despite favoring Marguerite’s sisters during their formative years, it is Marguerite that Zilda leans on during her later years, a reversal that the memoir treats with the complexity it deserves. The pattern of the middle daughter, overlooked in formation and relied upon in decline, is the book’s most quietly devastating and most universally recognizable insight, connecting the specific experiences of Lydie’s daughter and Zilda’s daughter to a pattern that millions of readers will recognize from their own family histories.

If you have ever been the middle daughter, or loved one, or suspected that the women in your family carried more private history than they ever disclosed, Middle Sisters by Marguerite Duvivier is the memoir that sees all of it and has the courage to write it down. Pick up your copy on Amazon today and discover what Zilda’s secret journals finally allow the world to know.

San Diego Trainer Peter Embiricos on Why One-on-One Coaching Still Beats the App Era

By: Matthew Kayser

Peter Embiricos is a personal trainer based in San Diego and is very much a one-on-one coach. In a market which is absolutely saturated with fitness apps, wearables, AI generated workout plans and on-demand classes, Peter has built his business on the traditional model of personal coaching. In this interview he talks us through how he works with clients, who he trains, why San Diego is such a good place to be active and why he thinks a real coach is still relevant in the app age.

For readers meeting you for the first time, how would you describe what you do?

Peter Embiricos: I’m a personal trainer in San Diego, and almost everything I do is one-on-one. I build customized programs around each client’s goals, fitness level, schedule and history. That might mean getting stronger, losing weight in a way that lasts, regaining confidence after a long break, or simply feeling better day to day. My job is part programming, part coaching and part accountability. The workouts matter, but the real work is helping someone build habits they can keep for years, not weeks.

Why did you build your practice around one-on-one coaching instead of group classes or online programs?

Peter Embiricos: Because no two people walk in with the same body, the same goals or the same obstacles. A group class has to be designed for the average person in the room, and most people aren’t average in any useful way. One person has a stiff lower back from sitting all day. Another hasn’t trained in five years and is nervous about getting hurt. Another is training hard but not eating enough to recover. When I’m working with one person, I can see those things and adjust in real time: the exercise, the load, the pace, even the conversation. That level of attention is where most of the progress comes from.

Fitness apps, wearables and AI workout plans are everywhere now. Why does a human coach still matter?

Peter Embiricos: Apps are very good at giving people information. What they can’t do well is read the person in front of them. An app doesn’t know that your squat changed because your knee is bothering you, or that you’re quieter than usual because work has been brutal this week.

It can’t tell when to push and when to pull back. Most people don’t fail because they lack a workout plan. There are thousands of free ones online. They fail because they don’t have the feedback, structure and accountability to stick with it. That’s what a good coach provides. There’s also something motivating about knowing a real person is expecting you on Tuesday at 7 a.m. That’s much harder to ignore than a push notification.

So are you against fitness apps?

Peter Embiricos: Not at all. I’ve talked about research showing fitness apps can help people move more over time, and I encourage a lot of my clients to use them. Tracking steps, sleep or workouts makes progress visible, and that’s a powerful motivator. The problem is when people treat an app as the whole solution. I see technology as a support tool. It’s great for the days between sessions, for spotting patterns and for keeping people engaged. The coaching itself, deciding what to change, when and why, still works best with a human involved.

Who do you typically work with?

Peter Embiricos: A real mix. Many of my clients are busy professionals who don’t have time to figure out what to do in the gym and want every session to count. Some are complete beginners who feel intimidated and need someone patient in their corner. Others are adults in their 40s, 50s and beyond who want to stay strong, protect their joints and keep doing the things they love. I also work with people coming back after a long break, whether that’s an injury, a new baby or a demanding few years at work, who are frustrated that they’ve lost ground. What they have in common is that they want results that last, not a 30-day challenge.

What does working with you look like, especially in the first few weeks?

Peter Embiricos: It starts with a conversation, not a workout. I want to know what someone’s goals are, what they’ve tried before and what got in the way. I also ask how they sleep, how they eat, what their days look like and whether they’re dealing with any aches or injuries. Then we look at how they move, starting with basic patterns like squatting, hinging, pushing, pulling and carrying. From there I build a program that meets them where they are. The first few weeks are about consistency and technique, not exhaustion. I’d much rather someone leave a session feeling capable and wanting to come back than wiped out and dreading the next one. Intensity can come later. Habits come first.

How do you approach nutrition with your clients?

Peter Embiricos: Simple and realistic. Nutrition advice is absolutely everywhere these days and there’s a new trend on social media every week. My approach is to go back to the fundamentals that have stood the test of time: sufficient protein intake, building your meals around whole foods, staying well hydrated and being consistent rather than perfect. I’d rather a client make three small changes that they can actually stick to than have them go all in on a Monday and then give up by Friday. Always bear in mind that nutrition and training go hand in hand. You can’t out-train a diet that’s not going to support your goals, but you don’t necessarily need a very fixed plan to make progress.

How does being based in San Diego shape the way you train people?

Peter Embiricos: San Diego is a fantastic place to be a trainer. The weather is ideal for outdoor training pretty much all year round and there’s a huge variety of terrain to work with (coastline, hills, trails, parks etc). I like to do as many of my sessions as possible outdoors when it’s appropriate for the client as it has a massive effect on their mood and makes the training seem less like a chore. It’s also a very active city and that helps in that people see their neighbours walking, surfing, hiking and running so staying active starts to become the standard rather than something you do as an obligation. That said, a lot of my clients are working out while travelling for work so one of the things I do is ensure that their routine doesn’t just go to pot the moment they leave town. I’ve actually got a few tips on how to stay fit whilst travelling as that’s such a common issue.

In an earlier interview, you said building mental resilience is just as important as building muscle. Do you still believe that?

Peter Embiricos: More than ever. As I said in that interview, physical results come from repetition and consistency, and both are driven by mindset. The clients who succeed long term aren’t necessarily the most talented or the most motivated on day one. They’re the ones who learn to keep going on the days they don’t feel like it. They don’t let one bad week turn into a bad month, and they measure progress over years instead of days. A big part of my job is helping people build that kind of resilience, and it tends to carry over into the rest of their lives too.

What’s your advice for someone trying to decide between a fitness app and a personal trainer?

Peter Embiricos: Be honest with yourself about what’s been holding you back. If you know what to do and you’re consistent, an app might be all you need. A coach makes the biggest difference if you’ve started and stopped several times, if you’re unsure about technique or working around an injury, or if you simply need someone to hold you accountable. And it doesn’t have to be one or the other. Some of my best results come from clients who use technology between sessions and come to me for the coaching, the adjustments and the support. The goal is the same either way: find something you can stick with, and keep showing up.

About Peter Embiricos

Peter Embiricos is a San Diego-based personal trainer who specializes in one-on-one fitness coaching. He designs customized programs focused on strength, sustainable weight management and long-term health for older adults, beginners, and busy professionals. His evidence-based approach combines personalized training, practical nutrition guidance and consistent accountability to help clients build habits that last.

How Much Money Do Parents Spend on Child Care?

Raising a child in the United States has always required careful budgeting, but child care costs have climbed sharply in recent years. According to ABC News, parents spend roughly $16,857 per year on child care. Over 18 years, that figure adds up to more than $300,000 for a single child. For many families, the yearly total rivals what they pay for housing or what a student might pay for a year of college tuition.

The financial strain hits hardest in the early years, when infants and toddlers need full-time supervision while their parents work. Families in larger cities and higher-cost regions often pay well above the national average. These costs can be hard to manage in a two-parent household, and they can become even more complicated when parents live apart. Knowing where the money goes can help parents plan ahead in an unpredictable economy.

What Expenses Are Factored Into the Costs of Child Care?

The costs of child care include far more than a monthly daycare bill. When families add up what they spend to raise a child, the list usually includes:

  • Daycare and preschool
  • Babysitters, nannies, and after-school programs
  • School materials
  • Groceries
  • Clothing and shoes
  • Health care
  • Housing and transportation

Other common expenses include extracurricular activities such as sports leagues, music lessons, and summer camps. While some of these costs are optional, many parents see them as an important part of their child’s growth and social life.

How Do Divorced Parents Handle Child Care Costs?

Divorced and separated parents share the duty to support their children, even when the children live mainly with one parent. In most cases, parents spell out how they will divide child care costs in a parenting plan or divorce settlement. If the parents cannot agree, a judge will decide based on state guidelines and the child’s best interests.

Many states treat work-related child care, such as daycare or after-school programs, as a separate cost that gets added to the basic child support amount. These costs are often split between the parents in proportion to their incomes. For example, if one parent earns 60 percent of the couple’s combined income, that parent may be responsible for 60 percent of daycare costs. Parents may also agree to split specific expenses, such as tuition, summer camp, or extracurricular fees, in a way that fits their family.

Clear communication and good records can prevent many disputes. Some co-parents may use shared calendars or co-parenting apps to track expenses and send reimbursement requests. Keeping receipts and invoices can provide both parents with a full understanding of what has been paid and what is still owed.

What Is Child Support Meant to Cover?

Child support payments cover a child’s basic living needs, such as food, shelter, clothing, and utilities. The goal is to give the child a stable standard of living in both homes, as close as possible to what the child would have had if the parents had stayed together. In general, the parent who receives support does not have to account for every dollar, as long as the money goes toward the household where the child lives.

Some costs may be handled separately from the basic support payment. Courts commonly order one or both parents to provide health insurance for the child and to share uninsured medical expenses. Child care for working parents, private school tuition, and special needs expenses may also be added on top of regular support, depending on the state and the family’s circumstances.

How Is Child Support Calculated in the United States?

Child support guidelines in the United States are set by each state, so the amount a parent pays can vary widely depending on where the family lives. Most states rely on one of three general models.

The income shares model is the most common. Under this approach, the state combines both parents’ incomes and estimates how much the parents would have spent on their children if they lived together. Each parent then pays a share of that amount based on their percentage of the combined income.

The percentage-of-income model bases support on a set percentage of the paying parent’s income. The percentage usually goes up with the number of children. Some states use a flat percentage, while others adjust the percentage as income rises or falls.

The Melson formula is used in only a few states. This model first sets aside enough income for each parent to meet their own basic needs. It then calculates the child’s basic needs and adds a share of any remaining income so the child can benefit from a parent’s higher standard of living.

Under any model, courts usually consider factors such as the number of children, how much time each parent spends with the children, health insurance costs, and support owed for children from other relationships. A judge may also depart from the standard formula when following it would be unfair or would not serve the child’s best interests.

What Can Parents Do to Enforce Unpaid Child Support?

Unpaid child support can leave a parent struggling to cover rent, groceries, and daycare costs, but the law gives parents several ways to collect what is owed. Every state has a child support enforcement agency that can help parents locate the other parent, establish or update an order, and collect payments. These services are often free or available for a small fee.

State agencies have strong collection tools. Common enforcement methods include withholding support directly from the paying parent’s paycheck, intercepting state and federal tax refunds, and placing liens on property such as homes or vehicles. States can also suspend driver’s licenses for failing to pay support.

A parent can ask the court to hold the other parent in contempt for failing to follow a support order. A judge may order fines, require payment plans, or in serious cases, sentence a person to jail time. When the paying parent lives in another state, uniform laws across the country allow child support orders to be enforced across state lines.

Past-due child support generally does not go away on its own, and some states add interest to unpaid amounts. A family law attorney can explain the options available in a particular state and help a parent take the right steps to recover the support a child needs.

Disclaimer: The content in this article is provided for general knowledge. It does not constitute legal advice, and readers should seek advice from qualified legal professionals regarding particular cases or situations.

Five Numbers a Business Owner Should Keep on One Page in 2026

By Dr. Tamara Patzer

In brief: Five figures sit behind most tax and estate conversations for owners near the top 1%: the income line, the top bracket, the investment income surtax, the capital gains rate, and the estate exclusion. Each is sourced to the IRS or the Tax Foundation, with a note from a New Orleans tax attorney on why how you own matters as much as what you own.

Tax talk gets abstract fast. Five numbers do most of the work for owners who are near, or already inside, the highest-earning tier. Here they are, with sources, followed by the idea that New Orleans tax and estate attorney Todd M. Villarrubia says ties them together.

What Is The First Number: The Income Line?

About $676,000. For tax year 2023, a filer needed roughly that much adjusted gross income to be in the top 1%, according to the Tax Foundation’s analysis of IRS data1. That group paid about 38.4 percent of federal individual income tax1. It is a snapshot of one year, and it moves.

Villarrubia opens his book, Entrepreneurial B.E.A.S.T. Mode™, with the reminder that the line is lower than many believe.

What Is The Second Number: The Top Bracket?

$640,600 for single filers, $768,700 for joint filers. For 2026, the 37 percent federal bracket applies to taxable income above those amounts, according to the IRS2. The IRS page announcing them is marked archival, so confirm current figures before relying on them.

Taxable income is not the same as adjusted gross income, so an owner can sit near the income line and still be below the top bracket, or the reverse. The point is to know both.

What Is The Third Number: The Investment Income Surtax?

3.8 percent. The Net Investment Income Tax applies to certain investment income when modified adjusted gross income is above $200,000 for single filers, $250,000 for joint filers, or $125,000 for married filing separately. Many owners learn about it only when a sale produces a gain on a return that is already large.

What Is The Fourth Number: The Capital Gains Rate?

20 percent. Long-term capital gains are taxed at 0, 15, or 20 percent, and an asset must be held for more than one year to qualify as long-term. For 2025, the 20 percent rate applied above $533,400 of taxable income for single filers and above $600,050 for joint filers. The IRS page gives no 2026 thresholds, so check the current year before planning a sale. The same page notes higher maximum rates of 28 percent for certain items, including collectibles and the taxable part of qualified small business stock.

What Is The Fifth Number: The Estate Exclusion?

$15,000,000. That is the 2026 federal basic exclusion amount per person, as the IRS lists it5. An owner whose company, real estate, and investments together pass that amount has a federal estate tax question unless the plan changes the answer.

What Do The Five Numbers Have In Common?

They all depend on how things are held, not only on what is owned. Villarrubia states the idea in two lines. The first is “Wealth preservation depends not on what you own, but on how you own it.” The second is “Structure is not merely an accessory to success; it is essential for its long-term survival.”

In his book, the point comes from the chapter on business structure. Different entities can be taxed differently depending on the elections filed with the IRS, and which one fits depends on the owner’s situation. An owner who knows the five numbers but has never asked how the assets are titled has only half of the picture.

He is just as direct about what goes wrong when nothing is done: “Wealth doesn’t fail because of taxes; it fails because of disorder.” In his telling, the numbers matter less than whether someone has put the pieces in order before they are needed.

Which Of The Five Usually Surprises Owners Most?

It tends to be the third, because it is not a bracket and does not show up on the tax tables most people look at. It is a separate tax with its own thresholds, and it sits on top of everything else. The estate exclusion is a close second. An owner with a $40 million company can feel modestly off because cash is tight, and still hold an estate well above $15,000,000. Both surprises come from the same cause: the balance sheet is mostly one illiquid asset.

A short exercise helps. Take the number you expect to pay on a sale and compare it with the cash you could actually raise without selling anything. If the second figure is far smaller, the owner has a liquidity gap, and closing it is a planning task that takes time.

How Can An Owner Use This List?

Write the five numbers on a single page and put your own next to each one: last year’s adjusted gross income, taxable income, investment income, any gain you expect from a sale, and your estimated estate. The gaps and surprises on that page are the agenda for a meeting with a licensed attorney and a tax professional.

How Should A Reader Keep These Numbers In Perspective?

As context, not as targets. Figures like these describe the country, and they are updated as new data arrives. The useful move is to ask what each one implies for your own household: a threshold you might cross in a sale year, a limit that could shape an estate, a rate that applies to a gain. Write down the one that matters most to you and bring it to your next meeting with your attorney and tax professional.

Common Questions

Do These Numbers Change?

Yes. Thresholds are adjusted regularly, and Congress can change rates and exclusions. Each figure above carries its year.

Are These State Numbers?

No. They are federal. State income tax and state estate rules can differ and are not covered here.

Is Crossing The Income Line A Problem?

No. It is information. It means a larger share of the planning questions applies to you.

Why Does The List Start With Income And End With Estates?

Because that is the order in which most owners meet them. Income comes first, a sale brings the gains and the surtax, and the estate exclusion arrives last, usually after the owner has stopped thinking about it. Planning tends to work better when the order is reversed and the end is considered first.

Sources

  1. Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023
  2. Internal Revenue Service, Tax inflation adjustments for tax year 2026
  3. Internal Revenue Service, Topic no. 559, Net Investment Income Tax
  4. Internal Revenue Service, Topic no. 409, Capital Gains and Losses
  5. Internal Revenue Service, What’s New: Estate and Gift Tax

About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.

About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; Website: Wealth Planning Law Group

Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.

Office, Coordinator, or Calendar and A One-Page Grid for Choosing

By: Dr. Tamara Patzer

October 12, 2026

In Brief: Families often assume the choice is a full family office or nothing. A New Orleans tax attorney lays out three paths instead: a full office, a part-time coordinator, or a calendar and a map, and gives a one-page grid for deciding among them, anchored in current national figures on wealth and generational transfer.

People tend to see the family office decision as a switch: build one or do not. In practice, there are at least three settings between off and on. A family can run a full office with its own staff. It can hire a part-time coordinator who works across the family’s advisers. Or it can start with a map and a calendar and see what that reveals. Todd M. Villarrubia, a New Orleans attorney who focuses on tax and estate planning, wrote Entrepreneurial B.E.A.S.T. Mode™ partly to help families tell which setting fits. This grid distills his reasoning.

Why Does the Choice Matter Now?

Because the volume of wealth about to change hands is large and the habits around it are not. Cerulli Associates expects $124 trillion to pass between U.S. generations through 2048, with $105 trillion to heirs and $18 trillion to charity1. Federal Reserve data show about $60.3 trillion of net worth held by the top 1% in the second quarter of 20262. Families at many levels will face questions about how their wealth is run, and not all of them need the same answer.

How Does the Book Describe the Origin of the Idea?

Modestly. Villarrubia writes, “The family office emerged not from theory but from necessity.” The line is a reminder that the form follows a need. A family should not adopt an office because others have one. It should adopt the amount of structure its situation requires.

What Is the First Path: A Map and a Calendar?

This is the lightest option and the right starting point for most families. It costs little: a page that lists entities, accounts, documents and advisers, and a calendar of deadlines and decisions. It adds one habit, a quarterly meeting where the advisers sit together.

It suits a family with a single company or a few assets, advisers who are willing to cooperate and no pressing transition. It is also the right test for everyone else. If a family cannot keep a page current and hold four meetings a year, it is not ready for something larger.

What Is the Second Path: A Coordinator?

A coordinator is a person who works across the advisers on the family’s behalf. The role may be filled by a trusted attorney, a senior financial professional or a part-time hire. Their job is to maintain the map, run the calendar, collect information and chase open items.

It suits a family whose affairs have outgrown a quarterly meeting: several entities, property in more than one state, a transition on the horizon or a next generation to bring in. The author notes that the arrangement should reflect the family’s goals and not just its balance sheet: “While similar to wealth management firms, family offices place a greater emphasis on personalized, long-term goals and legacy.”

What Is the Third Path: A Full Office?

A full family office has its own staff, systems and often its own legal structure. It handles investments, tax coordination, record keeping, family communication and sometimes lifestyle matters. It is a serious commitment of money and attention, and it makes sense when the volume of work justifies it.

The book calls it infrastructure for long horizons, and says the best ones see their role as larger than money: “The most successful family offices recognize that they’re not merely managing assets but stewarding family ecosystems.” That description fits a family with many members, many assets and a commitment to keep them together for decades.

What Does the Grid Look Like?

Score your family from one to three on each of five rows, with one meaning simple and three meaning complex.

  • Entities and accounts: a handful, a dozen or dozens.
  • Locations: one state, two or three, or many.
  • Family members involved: a couple, a group of adults or several households.
  • Transitions expected in five years: none, one or several.
  • Advisers: willing to cooperate, mixed or siloed.

A total of five to seven points suggests the first path. Eight to eleven suggests a coordinator. Twelve or more suggests exploring a full office. The numbers are a heuristic and not a rule, and a licensed attorney can say how they apply to a given family.

What About Cost?

It varies widely and no figure in this article should be taken as a benchmark. The sound comparison is between the cost of the structure and the cost of the problems it would prevent: duplicated fees, missed deadlines, conflicting advice, disputes. If the second set is larger, the case is made.

Income level alone does not decide it. The Tax Foundation’s analysis found that a filer needed about $676,000 of adjusted gross income in tax year 2023 to reach the top 1%3. Many families that need coordination are well below that line, and some above it do not need an office at all.

When Should a Family Move From One Path to the Next?

When the lighter arrangement stops working. Signs include missed deadlines, advisers who contradict each other, a family member who cannot find a document, or an event such as a sale or a death that shows how fragile the system is. Moving up in response to those signs is sensible. Jumping to the top path before a family has tried a lighter one often leads to disappointment.

The reverse is also possible. A family that built a large structure and finds it too heavy can simplify. The goal is a structure that fits.

What Do All Three Paths Share?

A single set of facts, a named person responsible and a regular meeting. The book says the real test is whether the family can afford to go without coordination, and the answer is rarely yes.

Common Questions

Can I try the first path myself? Yes. Bring the result to your attorney and tax professional for correction.

Do I need to decide today? No. Start with the map and revisit the grid in a year.

Who should I ask about the right level? A licensed attorney who works with business-owning families is a sensible first call.

Sources

  1. NAPA-Net, Wealth Transfers Expected to Hit $124 Trillion Through 2048 (reporting Cerulli)
  2. Federal Reserve Distributional Financial Accounts, Net Worth Held by the Top 1% (FRED)
  3. Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023

About the Author: Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.

About the Source: Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™.

Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124.

Phone: 504-982-8207

Email: todd@lawealthplan.com

Website: Wealth Planning Law Group

Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.

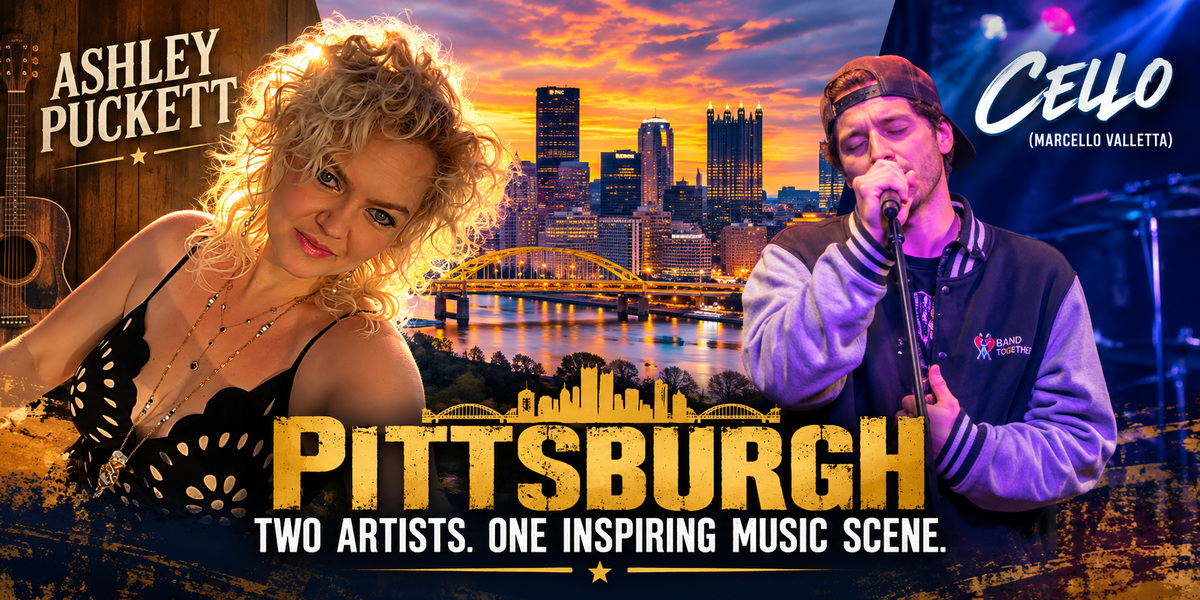
Steel City, Different Sounds, Ashley Puckett and Cello Are Redefining Pittsburgh’s Independent Music Scene

By: Steven Smith

From country heartbreak to genre-defying introspection, two Pittsburgh-area artists demonstrate why the Steel City remains a breeding ground for musical originality.

Pittsburgh has always been a city of contradictions. Its industrial backbone stands alongside a thriving arts community, its working-class traditions coexist with cultural experimentation, and its musical identity stretches from jazz legends and rock innovators to contemporary country singers and boundary-pushing alternative artists. Within that diverse landscape, two distinctive talents are helping write the next chapter of Western Pennsylvania’s musical story: country singer-songwriter Ashley Puckett and genre-fluid recording artist Cello, born Marcello Valletta.

At first glance, the two performers appear to have little in common. Puckett embraces country music’s familiar emotional vocabulary of heartbreak, devotion, and resilience, while Cello builds atmospheric musical experiences that blur the boundaries between alternative pop, hip-hop, poetry, and theatrical performance. Yet their creative journeys share an unmistakable thread: a commitment to personal expression, artistic independence, and the determination to build meaningful careers outside the industry’s traditional centers.

Ashley Puckett: Country Music With a Pittsburgh Backbone

For Ashley Puckett, the road to recognition began in North Huntingdon, Pennsylvania, just east of Pittsburgh. Growing up far from Nashville’s famous Music Row, she found inspiration in country music’s most expressive female voices, including Carrie Underwood, Miranda Lambert, Lee Ann Womack, and Sara Evans.

Her early musical development involved vocal competitions, community events, open-mic performances, and countless hours learning how to connect with an audience. By sixteen, Puckett had picked up the guitar and begun writing songs, gradually developing the personal approach that would become her trademark.

Her professional breakthrough arrived with the release of her debut album, Never Say Never, on February 14, 2020, through MTS Records. Produced with the involvement of Bryan Cole and a collection of accomplished Nashville musicians, the album introduced a singer capable of combining traditional country sensibilities with polished contemporary arrangements.

Early singles “Medicine” and “Bulletproof” helped establish her presence on independent country radio. “Bulletproof” reached number one on New Music Weekly’s AM/FM Country chart, while Puckett subsequently received the Gold Emerging Artist of the Year Award from the International Singer-Songwriters Association in 2022.

Her musical evolution continued with “What’s Her Name?” and “Tequila,” the latter becoming particularly significant because it represented a growing confidence in her songwriting. The track reached the Top 80 of the MusicRow CountryBreakout chart, demonstrating that a Pennsylvania-based independent artist could compete for attention within Nashville’s crowded radio landscape.

In 2024, Puckett released “Anchor,” a deeply personal song exploring emotional stability, devotion, and the power of standing beside someone through life’s difficulties. Co-written with Andrew Douglas and Nathan Beatty, the single revealed an increasingly mature artist interested in conveying vulnerability without sacrificing strength.

Now, Puckett is preparing another chapter with “Stone Cold Broken Heart,” a forthcoming single produced by Adam Ernst, whose credits include work connected to Bailey Zimmerman, Mickey Guyton, and Chase Matthew. The recording promises to return to country’s enduring fascination with romantic disappointment while introducing another layer of personal reflection.

For Puckett, the ongoing journey is not simply about climbing charts. It is about earning every step forward through perseverance and emotional honesty.

Cello: Breaking Musical Boundaries in the Steel City

Where Puckett relies on country’s storytelling traditions, Marcello Valletta, professionally known as Cello, takes a decidedly less conventional approach.

A singer-songwriter, published poet, and experienced actor, Valletta approaches music as an extension of a broader artistic identity. His work rejects easy classification, combining introspective lyricism, expressive vocal performances, and sounds drawn from multiple contemporary genres.

Those influences helped shape an artist who values experimentation as much as emotional accessibility. Rather than limiting himself to predictable musical structures, Cello treats individual songs as opportunities for confession, confrontation, and self-discovery.

That philosophy became especially apparent with his nine-track album Singing to Serpents, released March 1, 2026.

Featuring songs including “Stay Here,” “Elevate,” “Sucks to Be Used,” “Full Moon,” “Cravings,” “Pray,” and “Faith,” the project examines complicated emotional territory, moving between desire, frustration, spirituality, healing, and personal transformation.

The album’s greatest strength lies in its refusal to package difficult experiences into convenient answers. Its shifting moods reflect the unpredictability of real life, where confidence and insecurity frequently coexist.

Cello celebrated the record with a March 12th performance at Pittsburgh’s Spirit, connecting his increasingly adventurous recorded work with the city’s independent live-music community.

For Valletta, Pittsburgh provides an environment where different artistic disciplines can intersect without demanding conformity. His combination of music, poetry, and performance demonstrates the possibilities available to artists willing to challenge conventional definitions of popular music.

Two Artists, One Resilient Musical Community

Despite their stylistic differences, Puckett and Cello represent complementary sides of Pittsburgh’s evolving creative personality.

Both understand the importance of storytelling. Puckett communicates through recognizable country narratives, inviting listeners into experiences of love, disappointment, and perseverance. Cello works through a more abstract emotional vocabulary, using sonic experimentation to explore identity and internal conflict.

Their music also challenges outdated assumptions about geography. Nashville remains country’s commercial headquarters, while New York and Los Angeles dominate much of the national entertainment conversation. Yet neither artist has needed to abandon a Pittsburgh connection to develop an individual creative identity.

That independence reflects something fundamental about Western Pennsylvania’s artistic heritage: a willingness to work hard, resist expectations, and create something meaningful without waiting for outside approval.

Ultimately, Ashley Puckett and Cello illustrate the breadth of possibility within a single regional music community. One finds revelation inside the familiar contours of country music. The other searches for it through genre-crossing experimentation.

Their sounds may travel different roads, but both carry something unmistakably Pittsburgh: resilience, individuality, and the conviction that authentic voices deserve to be heard.

And in a music industry frequently preoccupied with imitation, that might be the Steel City’s greatest contribution of all.

Artist websites: Ashley Puckett | Cello (Marcello Valletta)

Stacy Nathaniel Jackson Built a Novel Out of Memos, Poems and Dream Journal Doodles

By: Francis Cooper

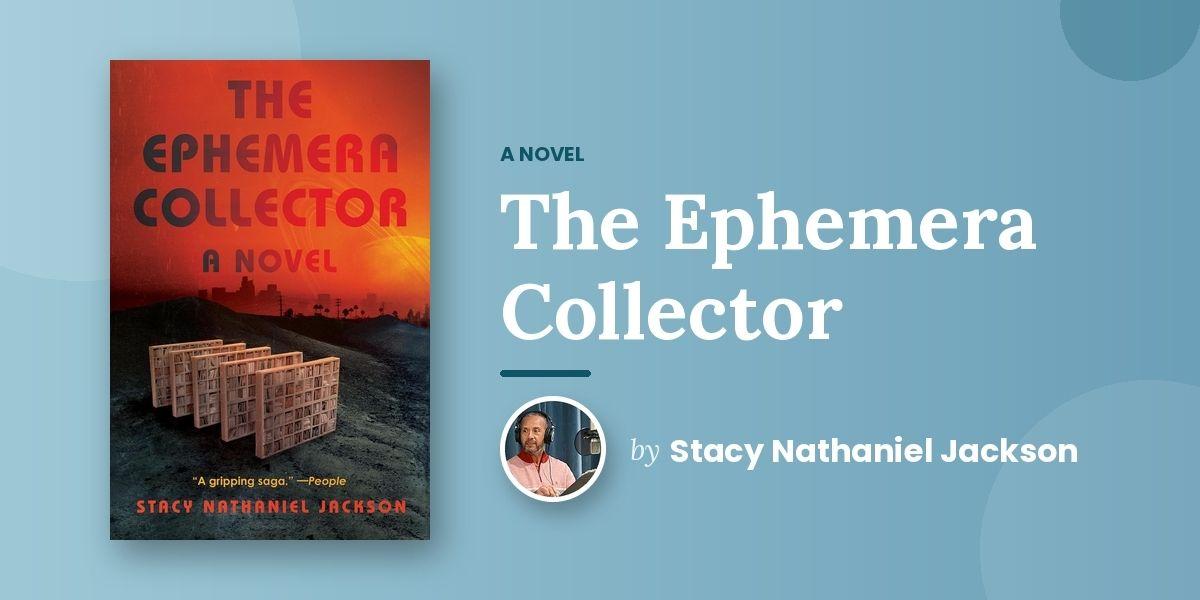
Reading The Ephemera Collector by Stacy Nathaniel Jackson is, as one critic memorably described it, like uncovering an archival box from the future, and that description captures something genuinely precise about the reading experience. Jackson has built his debut novel not as a conventional narrative but as a found collection, a mosaic assembled from prose chapters and poetry and memos and advertisements and dream journal doodles and transcripts and images and date-stamped photographs and documents of various kinds, all organized around the figure of Xandria Anastasia Brown, curator of African American Ephemera at the Huntington Library in 2035 Los Angeles, who is fighting to preserve what the future needs to remember while the world around her fractures under the pressures of climate disaster, social upheaval, and the specific terror of becoming a target in a world where AI systems are both your most reliable protectors and the most thorough collectors of data about you.

The novel has been called an ambitious homage to Octavia E. Butler, and the reference is accurate in the specific sense that Butler’s work is explicitly present in the narrative, not just as influence but as subject matter, embedded in the history of Diwata, the separatist underwater nation whose ephemera Xandria is collecting and whose political fate becomes one of the novel’s central concerns. But the comparison is also incomplete in the most interesting possible way, because what Jackson has done with the formal possibilities of the novel goes somewhere that Butler’s work, for all its genius, did not go, into the specifically ergodic, visually ambitious territory of House of Leaves and the experimental novel tradition, applied to Afrofuturist content with a confidence and a clarity of purpose that makes the formal ambition feel not indulgent but necessary.

Jackson makes audacious leaps through time and space across the novel’s length, from the immediate crisis of near-future California through ocean civilizations and the cosmos and a far-future symposium to the inner lives of the bots who are simultaneously protecting and surveilling Xandria, and the breadth of that imagination is matched by the precision of the questions it raises. The novel is deeply interested in what preservation costs, who gets to decide what is preserved, and what happens to a culture’s ability to understand itself when the archives are lost or corrupted or deliberately destroyed. Those questions have always been political, and Jackson renders their political dimension with the subtlety of a writer who understands that the most powerful speculative fiction does not illustrate a thesis but inhabits a contradiction.

Shortlisted for the 2026 William Saroyan International Prize for Writing, starred in Library Journal, named one of the best new science fiction books of the spring by multiple publications, and described by multiple critics as a singular new voice in fiction, The Ephemera Collector is the debut that its reception suggests and more.

If you want a novel that is formally daring, politically serious, emotionally resonant, and genuinely unlike anything else you have read, The Ephemera Collector by Stacy Nathaniel Jackson is exactly that book. Head over to Amazon and get your copy today and remember the name, because this is an author to watch.

Keith Leitner Is a Business Professor Who Co-Wrote a Children’s Book About Homophones

By: Sienna Whitmore

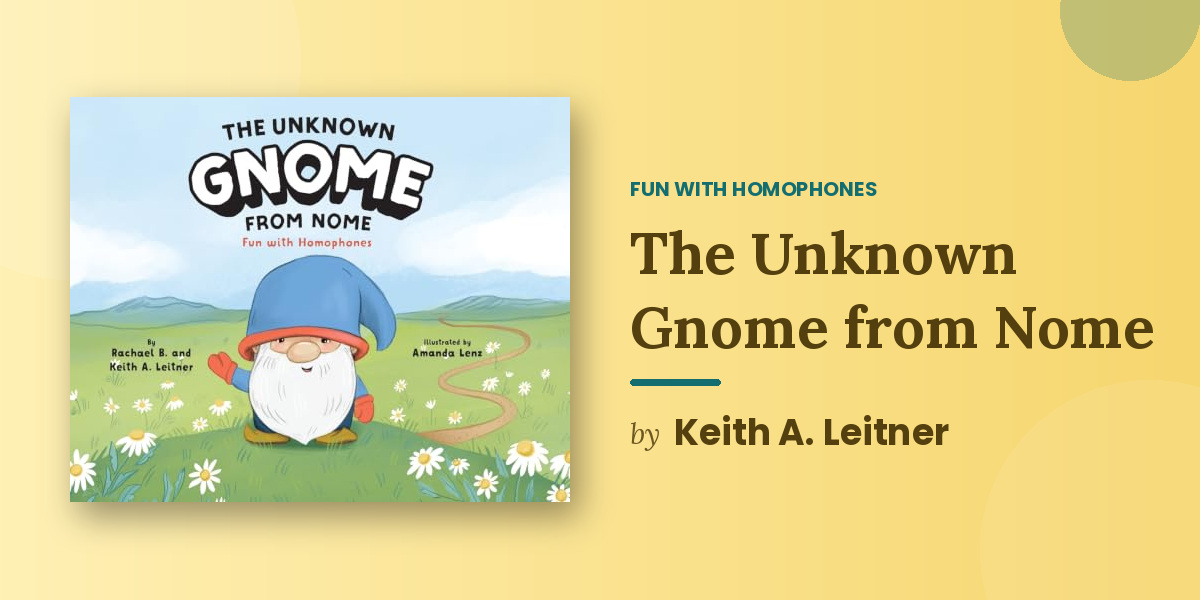
There is something refreshing about a children’s book written by someone who does not come from a children’s publishing background, who brings to the project the specific enthusiasm of a person who decided to make something because they wanted to make it rather than because it was their professional territory. Keith A. Leitner is a faculty member at the Haslam College of Business at the University of Tennessee, and the children’s book he co-authored with his wife about homophones represents a creative departure that he clearly enjoyed making enormously. That enjoyment is present throughout The Unknown Gnome from Nome in the specific way that genuine enthusiasm communicates itself through a text, giving the wordplay a liveliness and a warmth that more formulaic educational children’s books rarely achieve.

Homophones are among the most fertile sources of genuine comedy in the English language, and the Leitners have built their book around that comedic potential with a central premise that is genuinely inspired. A gnome from Nome, Alaska, whose name nobody knows, is the perfect protagonist for a story about words that sound the same but mean different things, because the character himself is a living example of the phenomenon, his gnome-ness rhyming with his home, his unnamed status making the know-no distinction both personal and playful.

The approach they have taken to vocabulary education reflects a genuine understanding of how children actually learn language, which is through encounter and repetition and the specific pleasure of recognizing a pattern rather than through the explicit memorization of rules. Each homophone pair the book introduces arrives in a narrative context that makes the distinction between the two words feel like a discovery rather than a lesson, which is the difference between vocabulary instruction that sticks and vocabulary instruction that evaporates the moment the test is over.

The book is available through Amazon, Barnes and Noble, and Books-A-Million, as well as through the authors’ own website at leitnerpublishing.com, reflecting the genuine investment the Leitners have made in getting this book into the hands of the young readers who will enjoy it most. The trailer they created for it captures the charm and the humor of the book itself, and the enthusiasm of the academic turned children’s author is entirely winning throughout.

If you are looking for a children’s book about homophones that earns its educational credentials through genuine humor and genuine storytelling rather than through earnest instruction, The Unknown Gnome from Nome by Keith A. Leitner is the book that makes vocabulary learning genuinely fun. Head over to Amazon today and get your copy for every young reader in your life who is ready to discover the funniest things about the English language.