Thursday, August 6
Business · Technology · Leadership

Luxury Safaris for US Honeymooners, Private Camps, Remote Lodges and Romantic Wild Places

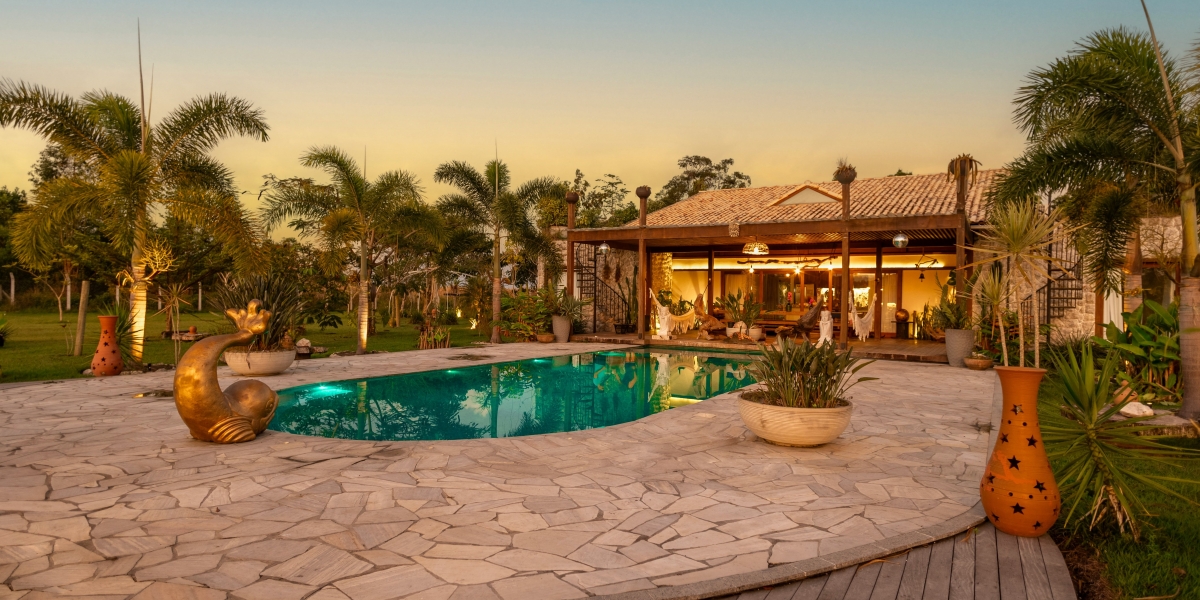
For US honeymooners, a luxury African safari offers something very different from a classic beach resort or city escape. It is intimate, adventurous and deeply memorable, with days shaped by wildlife, landscapes, quiet luxury and shared discovery. Instead of a honeymoon built around predictable relaxation, a safari gives couples moments that feel rare: lions moving through golden grass, elephants gathering at a waterhole, dinner beneath a wide night sky, or the first call of birds before sunrise.

The best honeymoon safaris are not about rushing from one famous destination to another. They are about privacy, rhythm and the right kind of comfort. Frank Steenhuisen, Co-founder and private guide at SAFARI FRANK, often encourages couples to think beyond a checklist of animals and focus on the feeling of the journey. A well-designed honeymoon should feel effortless, romantic and personal, while still keeping the wildness that makes Africa so powerful.

Why Safari Works So Well for Honeymoons

A honeymoon is not just another vacation. It marks the beginning of married life, so many couples want a trip that feels meaningful rather than ordinary. A safari naturally creates that sense of occasion. The days are structured enough to feel cared for, but unpredictable enough to feel alive. No two drives are the same, and many of the most memorable encounters happen without warning.

This is especially appealing for couples who want more than passive luxury. A safari combines comfort with presence. You are not simply checking into a suite and staying beside a pool for a week. You are waking early, tracking animals, crossing open landscapes, returning to camp for long lunches, and ending the day with sundowners as the light changes. The rhythm invites couples to slow down and pay attention together.

For many honeymooners, that shared attention becomes the real luxury. Phones are used less, conversations last longer, and the setting makes ordinary moments feel elevated. Even a quiet coffee before a morning drive can become part of the memory.

Private Camps and the Value of Seclusion

Private camps are often the strongest choice for honeymoon safaris because they offer intimacy without isolation. These camps are usually small, carefully positioned and designed to feel connected to the surrounding landscape. Instead of large hotel-style properties, couples can stay in tented suites, villas or lodges where the view, service and wildlife experience feel personal.

The most romantic camps are not always the most elaborate. Sometimes the appeal lies in a private deck, an outdoor shower, a plunge pool overlooking a riverbed, or a bed positioned so that the morning light enters gently through canvas. Good design keeps couples comfortable while preserving the sense of being in the bush.

Private concessions and conservancies can also make a major difference. They often allow fewer vehicles, more flexible guiding and a quieter safari atmosphere. For honeymooners, this means more space at sightings, more time with a guide, and more opportunities for private moments such as bush breakfasts, scenic sundowners or dinners away from the main camp.

Remote Lodges for a Deeper Sense of Escape

Remote lodges appeal to couples who want their honeymoon to feel far removed from everyday life. Reaching them may involve light aircraft flights, boat transfers or drives through wild country, but that journey is part of the experience. The farther the lodge feels from the ordinary world, the more powerful the arrival can be.

Botswana is one of the best destinations for this style of honeymoon. The Okavango Delta, Linyanti and other wilderness areas offer small camps, water channels, floodplains and exceptional guiding. A couple might move from a land-based camp focused on predators to a water-based lodge where mokoro trips, boat safaris and birdlife create a different pace.

In Tanzania, remote areas of the Serengeti or southern parks can create a similar feeling of space. Kenya’s private conservancies around the Masai Mara combine strong wildlife with a more exclusive atmosphere than busier reserve areas. Namibia offers a different kind of romance: desert lodges, vast horizons, dramatic dunes and silence that feels almost cinematic.

Choosing the Right Romantic Safari Style

Not every honeymoon safari should look the same. Some couples want classic big-cat sightings and dramatic plains. Others prefer wilderness, design, beach time, photography, walking safaris or a slower, more private rhythm. The right itinerary depends on what kind of romance feels natural to the couple.

East Africa works beautifully for honeymooners who dream of iconic safari landscapes. Tanzania and Kenya offer open plains, big skies, excellent wildlife and strong options for combining safari with Zanzibar, the Kenyan coast or other Indian Ocean beaches. This combination is especially attractive after a long flight from the United States because it creates a clear journey: adventure first, rest afterward.

Southern Africa suits couples who want variety. South Africa can combine Cape Town, the Winelands and a private safari reserve, making it ideal for travelers who enjoy food, wine, design and wildlife. Botswana is more remote and wilderness-focused, while Zambia can be excellent for couples interested in walking safaris and a more adventurous feel. Namibia is ideal for couples drawn to landscapes, photography and privacy rather than only big game density.

Comfort After the Long Flight From the United States

US honeymooners should plan the journey carefully. Africa is worth the distance, but the first days should not feel rushed. A smart itinerary may include an arrival night in a gateway city before continuing to a remote lodge. This gives couples time to recover from the long-haul flight, adjust to the time difference, and begin the safari rested rather than depleted.

The same applies to the end of the trip. Many couples choose to finish with a beach stay or a relaxed city stop before flying home. This gives the honeymoon a softer landing and avoids the stress of connecting from a remote airstrip directly to an international flight. A final buffer night can make the entire trip feel smoother.

Luggage planning also matters. Small aircraft often require soft-sided bags and lower weight limits than international flights. For honeymooners bringing special outfits, camera gear or beach clothing, it is important to pack with the most restrictive flight in mind.

Details That Make a Honeymoon Feel Personal

The most meaningful honeymoon details are often simple. A private dinner under the stars, a surprise picnic after a morning drive, a quiet afternoon with no scheduled activity, or a guide who understands when to linger and when to give a couple space can shape the emotional tone of the trip.

Couples should also be honest about their preferred pace. Some want every day full of activity. Others want fewer camp changes and more time to settle in. Three or four nights in a camp often feels better than two nights, especially on a honeymoon. It allows the couple to know the guide, understand the landscape, and relax into the rhythm of the place.

Romance on safari should never feel forced. The strongest moments usually come from the setting itself: the sound of lions at night, the warmth of a fire after dinner, the stillness of a private deck, or the shared silence when a herd of elephants passes close by.

A Honeymoon That Feels Wild and Personal

A luxury safari honeymoon works because it brings together contrast. It is adventurous and comfortable, remote and carefully hosted, wild and deeply romantic. For US couples traveling a long way, that combination makes the journey feel worthy of the occasion.

The best safari honeymoons are not the busiest or the most elaborate. They are the ones that match the couple’s style, choose camps with care, allow enough time to rest, and leave space for the unexpected. In private camps, remote lodges, and romantic wild places, a honeymoon becomes more than a beautiful trip. It becomes a shared story that begins with wonder.

About Frank Steenhuisen

Frank is the lead safari expert at specialists in exclusive safari adventures, SAFARI FRANK, helping travelers experience Africa’s wildlife safely and sustainably. Learn more at SAFARI FRANK.
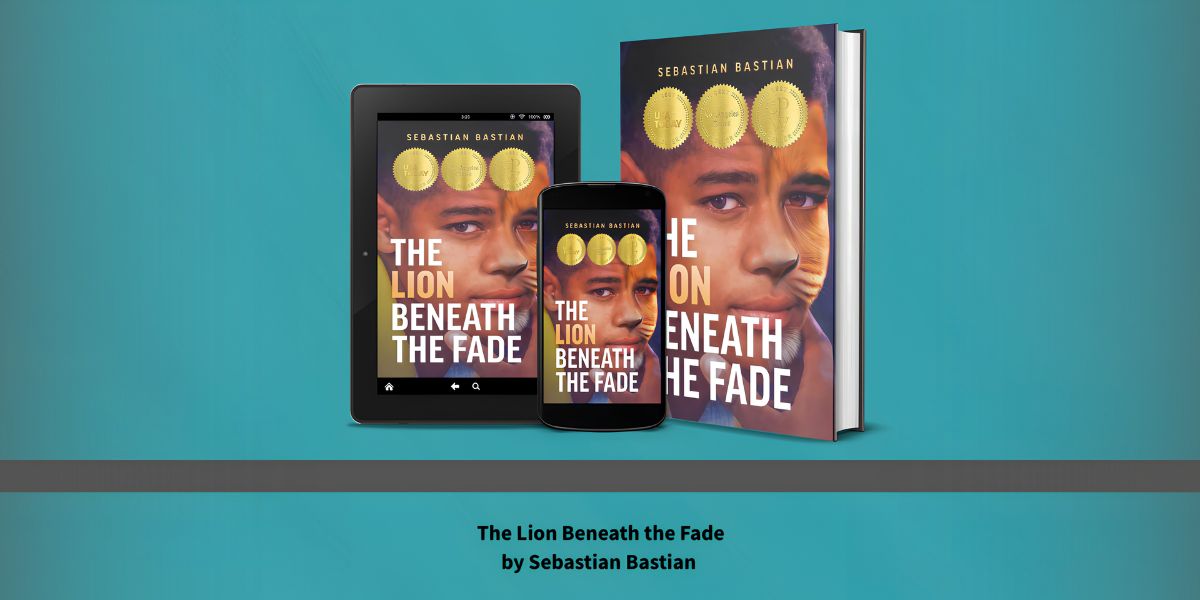
The Entrepreneur Who Built an Empire From a Small Island and Wrote the Book That Finally Explains How He Thought About All of It

By: Mt. Michaels

There is a particular kind of entrepreneurial story that gets told so often it has stopped meaning very much: the overnight success, the inspirational pivot, the dramatic turning point that changed everything. Sebastian Bastian is not telling that story in The Lion Beneath the Fade, even though the surface facts of his life would easily support it. He became a millionaire at nineteen, founded more than twenty companies across real estate, technology, logistics, and renewable energy, and was appointed his country’s Ambassador to Central America before most people have figured out what industry they want to work in. What makes this book genuinely worth reading is that he is far less interested in the impressiveness of those outcomes than in the specific thinking, the specific decisions, and the specific mindset shifts that made them possible for someone who started without shortcuts, connections, or a formal roadmap.

Reading this book produces the specific quality of engagement that comes from encountering someone who has actually done the thing they are writing about and has thought seriously enough about how they did it to offer something more useful than inspiration. Bastian writes with the directness of a person who learned early that clarity of thinking was among the most valuable assets available to someone without inherited advantages, and that directness carries through every chapter in a way that makes even the more conceptually demanding sections feel immediately accessible and immediately applicable.

The themes he explores stretch well beyond entrepreneurship into questions about identity, geography, and the particular challenge of building something significant from a place the world has not been conditioned to expect significance from. His insistence that local roots can become global reach rather than a limitation is not just an inspirational claim. It is an argument made through the specific story of how he built companies in The Bahamas that eventually extended their reach across Central America and the Caribbean, and that specificity gives the book a weight that purely abstract encouragement never achieves.

What particularly distinguishes The Lion Beneath the Fade from the crowded field of entrepreneurial memoirs is Bastian’s treatment of opportunity recognition as a learnable skill rather than an innate gift. His four-point framework for evaluating opportunities, built from lived experience across multiple industries and multiple market conditions, is one of the most practically useful contributions of the book. His call for political awareness as a genuine business skill is another distinctive contribution, reframing the external environment not as a background condition to be tolerated but as an active strategic domain to be understood and engaged.

Bastian has built something genuinely useful here, grounded in real experience and oriented entirely toward the practical question of how a person with more hunger than resources actually builds something that lasts. For anyone who has ever sensed that the conventional success narrative was not written for someone starting where they are starting, this book is the proof that the narrative was always too narrow.

Find The Lion Beneath the Fade by Sebastian Bastian on Amazon and discover the specific thinking behind one of the most remarkable entrepreneurial journeys in the Caribbean.

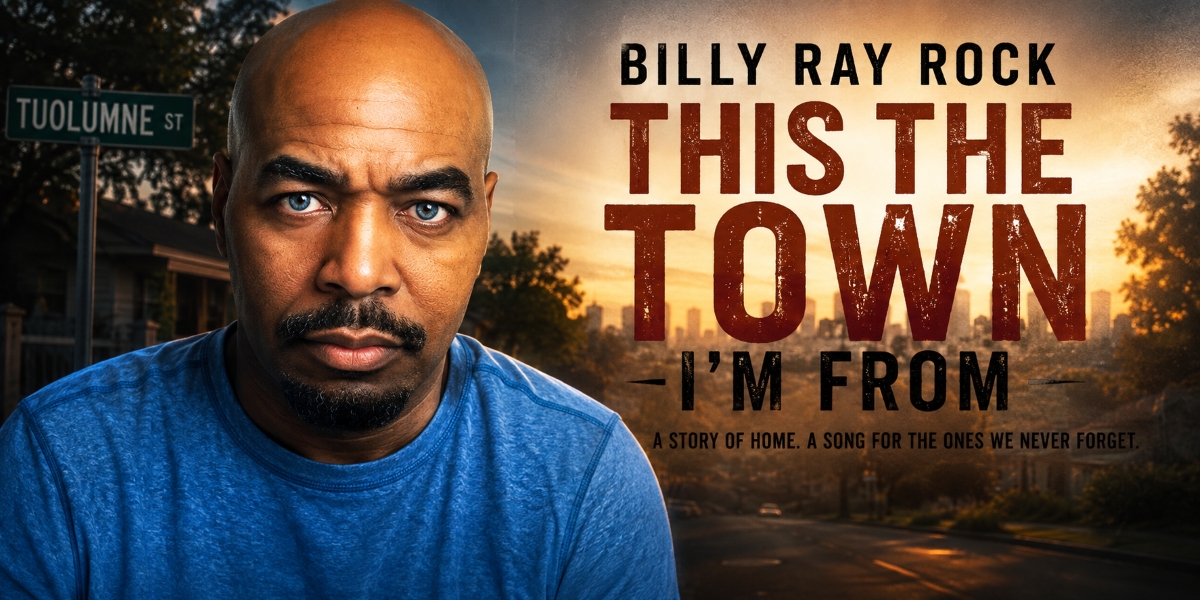
Billy Ray Rock’s “This the Town I’m From” Makes Memory Matter

Hometown songs are dangerous business. Write one badly, and you get tourism-board country: street signs, Friday nights, mama’s cooking, obligatory hardship, everybody raise a glass. Billy Ray Rock includes several of those ingredients on “This the Town I’m From” and somehow avoids most of the traps. The reason is simple enough. He isn’t selling Fresno. He’s mourning time.

Rock grew up on Tuolumne Street in Fresno, California, in a crowded house where money was scarce, and entertainment frequently meant whatever the kids could invent. He remembers walking barefoot to the store, playing with a water hose, county fairs, backyard moonshine, oxtails and greens, old folks dancing and young folks making noise. None of this sounds extraordinary until you understand that extraordinariness is precisely what Rock rejects.

He knows ordinary life becomes precious after it disappears.

“This the town I’m from / It’s small but made me strong,” goes the chorus, grammar left conversational because polishing it would defeat the point. This isn’t Billy Ray Rock presenting himself as the poet laureate of Fresno. It’s a grown man remembering how people actually talked, lived, ate, and survived.

And survival matters here.

The poverty of Rock’s childhood isn’t repackaged as heroic suffering. He has spoken about how growing up with little made commonplace comforts later feel almost like wealth. That’s a more complicated observation than the standard entertainment-industry narrative in which poverty exists mainly as Act One before fame arrives in Act Three. Rock understands deprivation as something that alters your measurements permanently.

Musically, his genre promiscuity suits him. Soul, R&B, hip-hop, blues and country storytelling coexist because Rock apparently sees little reason they shouldn’t. Growing up listening to radio that might move from Hall & Oates to the Ohio Players, Elton John to Earth, Wind & Fire taught him the useful lesson that genre classifications are principally somebody else’s administrative problem.

If it feels good, use it.

That attitude gives “This the Town I’m From” an appealing lack of anxiety. It doesn’t spend four minutes desperately informing you what demographic should enjoy it. The song simply settles into its story and lets Rock’s voice do what matters most: communicate.

Which brings us to death.

Rock originally populated this song’s emotional rearview mirror with parents, siblings, and other people who had vanished from his life. Then his wife died. She had been profoundly affected by the song and its accompanying video; Rock has said she could barely watch the video because of the emotions it stirred. Now the record contains another ghost.

That changes everything without changing a note.

Suddenly “My folks have come and gone” isn’t merely nostalgic bookkeeping. It’s the organizing principle. People disappear. Houses remain. Somebody else moves in. Their kids run around the rooms where yours once did. Eventually they leave too. The building doesn’t care.

Rock does.

His smartest lyrical turn comes when recollection gives way to instruction. “Life is short, kids grow up fast,” he observes, before urging listeners to hold their people close. Hardly a revelation, except that pop music has spent seventy years demonstrating that familiar truths become clichés only when the singer doesn’t believe them.

Rock believes this one.

Fatherhood has apparently accelerated his move away from the artist’s most boring obsession: himself. He has said that raising his two youngest children means more to him than his musical accomplishments and that losing his wife altered his relationship with artistic recognition. Once, making a great record meant enjoying some of the “shine” that came with being its creator. Now he’s more interested in whether the song gives somebody else a few meaningful minutes.

That’s maturity, which rock criticism traditionally treats with suspicion because maturity frequently means acoustic guitars, tasteful production, and nobody having any fun. But Rock’s version is different. His maturity means understanding that legacy isn’t how brightly the spotlight hits you. It’s what survives after somebody switches it off.

“This the Town I’m From” occasionally risks sentimentality because sentiment is its subject. It repeats its central idea because choruses do that. And its hometown imagery could sound familiar, detached from the life behind it.

But detach it, and you’ve missed the record.

The song works because Tuolumne Street isn’t symbolic to Billy Ray Rock. It’s Tuolumne Street. The barefoot kid was him. The crowded house was his. The dead are his dead. Fresno isn’t shorthand for blue-collar authenticity. It’s where the memories happened.

And that specificity is what permits everybody else inside.

You don’t need to have grown up poor in Fresno. Substitute your street. Your kitchen. Your siblings. Your stupid childhood game. Your mother’s food. Your person who isn’t there anymore.

Then Rock’s hometown song becomes yours.

“This the Town I’m From.” Turns out nostalgia improves considerably when somebody remembers what it costs.

Tushneem Dharmagadda Has a Name for the Cost Hiding Inside Your HR Tech Stack

By: Alex Morgan

Every company evaluating HR software this year is being sold some version of the same pitch: AI included, often at little or no extra cost. Tushneem Dharmagadda has seen this pattern before, and he doesn’t think it ends the way most buyers assume.

A Pricing Model Built to Change Later

As founder of workforce platform HubEngage, Dharmagadda watches AI pricing evolve across the HR tech market from the inside. His read on it is blunt: vendors are bundling AI into their core products now because early customers wouldn’t pay extra for it as a standalone feature, not because the economics of unlimited AI usage are sustainable long-term. He points to Uber and Netflix as the closest precedent, both once cheaper than the alternatives they replaced, both eventually raising prices once the market had adjusted around them and, in Netflix’s case, once the market fragmented into a dozen competing subscriptions that add up to more than the cable bill they replaced.

“I’m not saying companies should avoid AI,” he says. “I’m saying they shouldn’t assume today’s bundled or subsidized pricing is what they’ll be paying three years from now.”

The risk, in his view, isn’t any single vendor’s price increase. It’s a company ending up with AI billed separately inside its HR system, its communications platform, and half a dozen other tools at once, each reasonable on its own, all of it adding up to something nobody at the company actually tracks.

The Cost Nobody Puts on a Spreadsheet

Dharmagadda has a name for what happens after a company buys the cheapest tool for every individual problem instead of one connected system: workforce experience debt. Every additional login, every separate interface, every tool with its own narrow chatbot compounds into a workforce that no longer knows where to go for a simple answer.

“Every new tool adds another login, another interface, another place employees have to search for information,” he says. “Over time, they no longer know where to go to get an answer or complete a task.”

The framing borrows its logic from technical debt, the accumulating cost of shortcuts an engineering team eventually has to pay down. Dharmagadda’s version applies the same idea to HR technology: a company can keep adding tools that each look affordable on their own, while the real cost quietly builds in integration work, administrator time, training, and a fragmented daily experience for the employee stuck working across all of it. None of that shows up on the invoice for any single tool, which is exactly why it goes unmeasured for so long.

Where AI Actually Earns Its Keep

Dharmagadda isn’t opposed to AI in HR tech; he’s opposed to treating every feature as equally transformative. The category where he sees the clearest value is bulk content analysis. A chatbot can answer policy and procedure questions instantly, provided the underlying content is organized well enough to make that possible, and he points to survey analysis as an even clearer case. HubEngage’s own AI tools sort open-ended employee responses into more than 40 recurring themes automatically. HR teams have traditionally handled that kind of sorting by reading through every submission by hand. Those are the high-volume tasks he thinks are worth automating.

What he’s skeptical of is the smaller stuff sold as major ROI, an AI feature that helps someone write a slightly better email, marketed with the same enthusiasm as a tool that takes on a full manual review cycle. Time saved on a small task, he notes, doesn’t automatically translate into payroll actually eliminated, a distinction he thinks gets lost in most vendor pitch decks.

Why This Becomes a Leadership Problem, Not a Departmental One

The deeper issue Dharmagadda describes isn’t really about any single tool. It’s that most organizations buy workforce technology one department at a time. Communications picks its own platform. Engagement sits in a different budget. Operations runs its own systems. Each purchase looks reasonable in isolation because nobody is responsible for the total cost across the company. That’s the structural reason tool sprawl persists even at companies that are otherwise disciplined about spending elsewhere.

HubEngage’s pitch is built around collapsing that fragmentation: one platform spanning communications, operations, engagement, and microlearning, with native functionality where a company needs it and the ability to integrate with systems already in place where it doesn’t. The goal isn’t replacing every existing tool; it’s reducing how many separate places an employee has to check to get through a workday, and giving one team, rather than four, visibility into what the whole stack actually costs.

The Reckoning Dharmagadda Sees Coming

Two years out, Dharmagadda expects companies to start noticing how many times they’re effectively paying for the same AI capability. His example: an organization running four workforce systems, each with its own embedded chatbot, buys a “super chatbot” layered on top so employees only have to ask one place. The experience improves, but the company is now paying for AI in all four underlying systems plus the new layer plus the integrations connecting everything. Once usage-based pricing replaces today’s bundled allowances, all of those costs can climb at once, and nobody budgeted for that compounding effect because each piece was purchased separately, at a different time, by a different department.

The platforms he expects to hold up aren’t the ones with the most AI features. They’re the ones built to use intelligence that already exists inside connected systems rather than rebuilding it again in a new layer stacked on top, an architecture question he thinks emerging standards like MCP may eventually help resolve, though he’s careful to note that outcome still depends on how vendors choose to price access rather than on the technology itself.

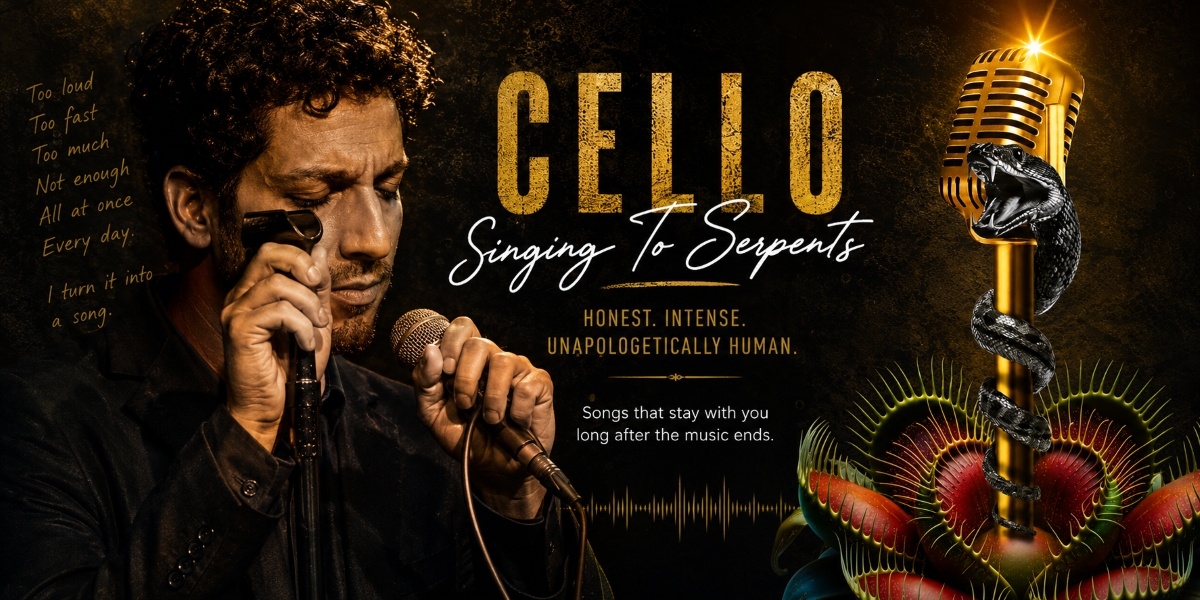
Cello Against the Noise: Music, Neurodivergence and the Strange Art of Being Yourself

By: Marcus Ellington

The music business has always had a peculiar relationship with outsiders. It worships them after they become successful and tries desperately to straighten them out beforehand. Every generation produces artists who are told they are too strange, too intense, too complicated, too difficult to categorize, and then, if fortune smiles, those very qualities become the mythology upon which careers are built.

Enter Cello, an artist for whom being different isn’t a costume purchased at some fashionable boutique of rebellion. It is simply the condition of existence.

Cello is autistic and has ADHD, facts that could easily become promotional shorthand in an era when identity is routinely compressed into hashtags. But reducing Cello to his neurodivergence would miss the point spectacularly. Autism and ADHD aren’t gimmicks attached to the music. They are elements of the perceptual machinery producing it.

And that distinction is important.

Cello’s career has increasingly been built around turning internal experience into public communication. His music inhabits those uncomfortable territories where anxiety rubs against hope, isolation encounters connection, and identity becomes something constantly examined rather than permanently settled.

His album Singing to Serpents may be the clearest expression of that artistic personality.

Even the title sounds like something from mythology: the musician standing before creatures traditionally associated with danger, temptation, knowledge, and transformation, attempting not to kill them but to communicate with them.

That’s practically a definition of songwriting.

Cello doesn’t run from emotional serpents. He sings to them.

The record moves through questions of belonging, self-acceptance, fear, faith and resilience without pretending that three minutes and a catchy chorus can solve them. There is something refreshingly unfashionable about that approach. Much contemporary pop arrives determined to tell listeners exactly how they should feel. Cello seems more interested in documenting what feeling actually resembles when nobody is watching.

His neurodivergence inevitably becomes part of this equation.

Autism and ADHD can influence attention, sensory experience, communication and the way an individual processes the surrounding world. For an artist, those differences can become creative materials. Cello’s work frequently carries the sensation of someone examining emotional details under magnification, noticing contradictions and textures that another songwriter might discard on the way to the chorus.

Then there is intensity.

Popular music desperately needs intensity, although the industry frequently attempts to manufacture it. Producers add another guitar, another vocal track, another beat, another digital explosion.

Cello’s intensity originates somewhere else.

It comes from investment.

You sense that these songs matter to the person singing them. The difference is enormous. Technology can make practically anyone sound dramatic. It cannot make someone sound invested.

That sincerity has helped Cello develop an artistic identity in which vulnerability isn’t presented as weakness or heroic triumph. It simply exists. There are doubts. There are victories. There are moments when the world makes sense and others when it appears to have been assembled without consulting the instruction manual.

In other words, there is life.

That may explain why the neurodivergent aspect of Cello’s story has relevance beyond biography. There are young musicians, writers, and artists growing up believing that success requires sanding away whatever makes them unusual. Social media has only intensified the contradiction. Everyone is encouraged to “be authentic,” provided that authenticity fits neatly into a fifteen-second video.

Cello offers another possibility.

Don’t eliminate the difference.

Investigate it.

Turn it into something.

His career suggests that the peculiarities of perception, the obsessive focus, emotional intensity, unconventional associations, and restless movement of thought can become artistic resources when given structure. Music supplies that structure. Rhythm organizes chaos. Melody gives emotion somewhere to travel. Lyrics transform private thought into something another human being can recognize.

That is where Singing to Serpents becomes more than an album title.

The serpent can be anxiety. It can be self-doubt. It can be the expectations of other people. It can even be the music industry itself, forever whispering that an artist might become successful if only he became slightly more like somebody already successful.

Cello’s answer appears to be remarkably simple: keep singing.

There is no guarantee attached to that philosophy. Independent music rarely offers guarantees. Careers rise, disappear, return, and mutate. Algorithms change. Audiences move elsewhere. Yesterday’s indispensable platform becomes tomorrow’s digital ghost town.

What survives is identity.

Cello has one.

He is a neurodivergent artist making emotionally candid music in an industry frequently devoted to emotional simulation. His autism and ADHD are neither tragic obstacles nor magical superpowers. They are pieces of a complicated human being whose particular way of experiencing the world has helped shape his particular way of making music.

And perhaps that’s the most interesting thing about Cello.

He isn’t asking the world to overlook what makes him different.

He’s asking us to listen to what happened because of it.

Business Term Loans vs Working Capital Advances: Which One Actually Fits Your Situation

A bakery owner I know spent an entire weekend confused between two financing offers that looked, on the surface, remarkably similar. Both promised roughly $35,000. Both came from reputable direct lenders. Both had reasonable sounding terms. What she couldn’t figure out was why one was structured so differently from the other, and more importantly, which one actually made sense for what she needed the money for. That confusion is incredibly common, and it usually comes down to not understanding the fundamental difference between a term loan and a working capital advance.

These two products get discussed almost interchangeably in casual conversation, but they’re built for genuinely different purposes, and picking the wrong one for your specific situation can quietly cost you more than the interest rate alone would suggest.

The Structural Difference That Actually Matters

A business term loan works the way most people instinctively think a loan works. You receive a lump sum up front, and you repay it over a defined period through regular, typically monthly, payments at a set interest rate. The total cost is generally lower relative to the amount borrowed, and the repayment structure tends to be more predictable, since you know exactly what you owe each month and exactly when the loan will be fully repaid.

A working capital advance operates on a different rhythm entirely. Rather than a fixed monthly payment stretched over months or years, repayment typically happens through smaller, more frequent deductions, often daily or weekly, pulled directly from your business bank account or as a percentage of your revenue. The total repayment period tends to be considerably shorter, often measured in months rather than years, and the pricing structure frequently uses a factor rate rather than a traditional interest rate.

Why the Repayment Rhythm Changes Everything

This difference in repayment frequency isn’t just a technical detail, it fundamentally changes how each product feels to actually live with as a business owner. A term loan’s monthly payment is predictable and easy to plan around, but it also means a large chunk of cash leaves your account all at once each month regardless of how that specific month is performing.

A working capital advance’s daily or weekly deductions are smaller individually, which can make cash flow feel less disruptive on any single day, but the cumulative effect requires careful attention since those small deductions add up continuously rather than in one predictable monthly event. Business owners with naturally variable daily revenue, restaurants, retail stores, service businesses with fluctuating client volume, often find this rhythm easier to manage than a fixed monthly obligation that doesn’t care whether this particular month was strong or weak.

Matching the Product to the Actual Purpose

The single most useful question to ask yourself before choosing between these two products is how long the benefit of the financing will actually last. If you’re funding something with a long, ongoing return, a piece of equipment that will generate revenue for years, a location buildout, a major hire whose value compounds over a long period, a term loan’s longer repayment period genuinely matches the timeline of the benefit you’re capturing.

If you’re funding something short term and specific, bridging a seasonal gap, covering a temporary cash flow crunch while waiting on a large receivable, capturing a time sensitive inventory opportunity, a working capital advance’s shorter repayment window matches that shorter term need far more naturally. Using a long term loan for a short term need means you’re potentially paying interest on capital long after you’ve already captured the benefit it was meant to fund. Using a short term advance for a long term need means facing a repayment pace that may not give the investment enough time to actually generate the return you were counting on.

The Cost Comparison Nobody Explains Clearly

Comparing the actual cost between these two products requires converting both to the same unit of measurement, since a term loan’s interest rate and a working capital advance’s factor rate aren’t directly comparable numbers. The only honest comparison is total dollars repaid for a given amount borrowed over a realistic timeline for each product.

A $30,000 term loan at a reasonable interest rate repaid over three years might total $34,000 to $36,000 in repayment. A $30,000 working capital advance repaid over six months might total $37,000 to $39,000. On the surface, the term loan looks cheaper, and for that specific comparison, it typically is. But that comparison only holds if you actually qualify for the term loan’s longer approval timeline and more extensive documentation requirements, and if your situation can genuinely wait for that process rather than needing capital within days.

Qualification Requirements Tend to Differ Too

Beyond cost and structure, these two products often have meaningfully different qualification thresholds. Term loans, particularly from banks, tend to require longer operating history, stronger personal credit, and sometimes collateral, reflecting their longer commitment and typically lower cost. Working capital advances, especially from direct lenders using automated underwriting, tend to have more accessible qualification standards precisely because the shorter repayment period and higher pricing offset some of the additional risk the lender takes on.

This means the choice between these products isn’t always purely about preference. A newer business or one with a less established credit history may simply have more realistic access to a working capital advance than to a traditional term loan, regardless of which product would theoretically fit their need better. Direct lenders including fundivi offer both structures, evaluating each application against bank account performance to help determine which product a specific business actually qualifies for rather than forcing every applicant into a single rigid category.

A Side by Side Look at Real Numbers

It helps to see this comparison worked out concretely rather than in the abstract. Consider two businesses each borrowing $30,000. The first takes a term loan at nine percent interest repaid monthly over three years, ending up with total payments somewhere around $34,300, spread out at roughly $953 per month. The second takes a working capital advance at a 1.3 factor rate repaid over six months through daily deductions, ending up owing $39,000 total, deducted in smaller increments of roughly $300 per business day.

The term loan clearly costs less in total dollars. But notice what each business is actually solving for. The first business has three years of predictable, lower monthly payments it can plan around easily. The second has a much shorter total commitment, fully repaid within six months rather than stretching across three years, which matters enormously if that business expects its financial picture to look completely different by the time next year arrives. Neither structure is objectively better. They’re simply optimized for different situations, and the right choice depends entirely on which situation actually describes your business right now.

Making the Actual Decision

For the bakery owner, the answer turned out to be straightforward once she articulated what she actually needed the money for. She wanted to fund a new commercial oven that would let her take on wholesale accounts, a purchase with a return that would play out over years, not months. A term loan with a longer repayment period matched that timeline far better than a working capital advance would have, even though the working capital offer had promised faster access to funds she didn’t actually need that urgently.

That’s really the exercise every business owner should walk through before signing anything. Write down exactly what the money is for and how long you expect the benefit to last. Then match the repayment structure to that timeline rather than to whichever offer arrived first or sounded the most familiar. The right product isn’t universally better, it’s the one that actually fits the shape of your specific need.

There’s one more question worth asking yourself honestly before you decide: how confident are you in your ability to predict your business’s cash flow over the full repayment period. A term loan’s fixed monthly payment assumes a certain baseline stability that a genuinely unpredictable business might struggle to assure three years out. A working capital advance’s shorter horizon means you’re only committing to a repayment pace you can reasonably forecast for the next several months, which for many business owners feels like a far more manageable promise to make to themselves. Neither answer is wrong. It just depends on how much certainty you actually have about where your business will be a year or three years from now, and being honest about that uncertainty is often the most useful part of the entire decision.

What to Consider Before Cutting a Loved One Out of Your Will in 2026

Deciding to leave a family member out of your will is rarely easy. Even when the reasons feel clear to you, the decision can carry emotional weight, and it can also open the door to legal challenges after you are gone. Family relationships are complicated, and estate plans often come with years of history that outsiders cannot fully see.

If you are thinking about disinheriting a spouse, child, sibling, or other relative, it helps to understand how the law treats these decisions. A will that is not written carefully can be challenged, delayed, or even overturned in court. An estate planning attorney can help you put your wishes into a document that holds up to scrutiny and reflects your true intentions.

Common Reasons People Choose to Cut Somebody Out of an Estate Plan

You may choose to leave a relative out of your will for many personal reasons. Some common examples include:

• A long history of estrangement or a broken relationship with the family member

• Concerns that the person would mismanage or waste an inheritance

• A belief that the person is already financially secure and does not need the assets

• Substance abuse or a pattern of harmful behavior

• A desire to leave more to a caregiver who provided years of support

• Financial gifts that you have already given to a family member

Every family’s situation is different, and there is no single right reason to disinherit someone. What matters most is that the decision is documented clearly and legally, so it is less likely to be challenged after your death.

What Is the Legal Process of Disinheriting Someone From a Will?

The legal process of leaving someone out of a will can vary somewhat depending on where you live, but a few general principles apply almost everywhere. First, your will must be signed and witnessed according to the laws of your state. If these formalities are not followed, the entire document could be at risk of being thrown out.

Second, many states require you to name the person you are excluding, or at least make clear that the omission was intentional. This step can prevent a court from assuming that you simply forgot about a close family member when the will was written.

Third, spouses often have special legal protections. In many states, a spouse cannot be fully disinherited, since the law grants a surviving spouse the right to claim a portion of the estate regardless of what a will says. Children usually do not have this same level of automatic protection, though the details may differ by state.

Working with an estate planning attorney can help you avoid mistakes that could unravel your plans later. A lawyer can also advise you on state-specific rules that might affect how your wishes will be carried out.

What Is a No-Contest Clause in a Will?

A no-contest clause, sometimes called an in terrorem clause, is a provision that discourages beneficiaries from challenging a will. Under this type of clause, a person who contests the will and loses can forfeit whatever inheritance they were originally set to receive.

The goal of a no-contest clause is to make a beneficiary think carefully before moving forward with estate litigation. If a disinherited family member believes they might have a case, a no-contest clause raises the stakes of pursuing that challenge. That said, some states limit how these clauses can be enforced, and courts may still allow a challenge if there is evidence of fraud or another serious problem with the will.

How Allegations of Undue Influence Could Affect Your Will

Undue influence is one of the most common grounds used to challenge a will. This type of claim may arise when someone alleges that a person used pressure, manipulation, or control to convince the person making a will to change their estate plan in a way that benefited the influencer.

Undue influence claims often surface when a caregiver, new spouse, or close companion receives a larger share of an estate based on changes that were made shortly before the person’s death, especially if that change was a departure from an earlier will. In these cases, courts may examine several factors, including the vulnerability of the person who made the will, the level of trust placed in the alleged influencer, and whether the changes seem consistent with the person’s known wishes.

Estate planning attorneys point to a few patterns that tend to insulate a will from this kind of challenge. Independent legal counsel matters. So does documenting the reasoning behind significant decisions, and making changes at a point well removed from any decline in health or heavy reliance on a single caregiver. Courts weighing these disputes give real weight to a clear paper trail, which makes intentions harder to question after the fact.

Can You Disinherit a Family Member Without a Will?

If you die without a valid will, state intestacy laws will decide how your property is divided. These laws follow a fixed order of priority, usually starting with your spouse and children, then moving to parents, siblings, and more distant relatives if no closer family members exist.

Intestacy laws do not consider your personal history, estrangement, or your actual wishes. If you die without a will, a family member you would have preferred to exclude could still inherit a share of your estate simply because of their legal relationship to you. This is one of the strongest reasons to create a will rather than leaving these decisions up to state law.

Disclaimer: This article is intended for general informational and educational purposes only. It does not provide legal, tax, estate planning, probate, financial, or professional advice, and it should not be relied upon as a substitute for guidance from a qualified professional. Will requirements, disinheritance rules, spousal rights, no-contest clauses, undue influence claims, intestacy laws, and estate litigation outcomes can vary by state, court, family circumstances, and applicable law. Readers should consult a licensed estate planning attorney, probate attorney, tax professional, financial advisor, or other qualified professional before creating, changing, or relying on any estate plan.

How Do You Access Business Funding Without Pledging Any Collateral?

Businesses built on services, knowledge, client relationships, and digital assets have few or no pledgeable physical assets to offer a lender. Performance-based direct lending addressed this by building underwriting models accurate enough to assess repayment probability from cash flow data alone, making collateral unnecessary for the evaluation of short-term capital risk.

The traditional collateral requirement served a specific and rational purpose in lending markets where assessing repayment probability required historical documents that could be manipulated, credit histories that could be thin or misleading, and business projections that could be optimistic to the point of uselessness. When lenders could not reliably assess whether a business would repay from future revenue, they required a specific asset they could claim in a default scenario as the financial backstop that covered the uncertainty.

Performance-based AI underwriting eliminates most of this uncertainty by evaluating what the business is actually doing right now. Twelve months of primary bank account transaction data provides a direct window into actual revenue volume, revenue consistency, cash management quality, existing debt obligations, and business cash flow patterns that are harder to manipulate than any document-based assessment. When the repayment probability assessment is based on this quality of real-time evidence, the collateral backstop becomes less necessary for the lender and more genuinely removable for the borrower.

What No Collateral Means in a Working Capital Agreement

No collateral in the working capital advance context means that no specific business asset is named in the agreement as pledged security against the advance. That covers equipment identified by serial number, a vehicle identified by VIN, and property identified by address. In a default scenario, the lender cannot repossess a specific designated asset. The business’s operational assets remain unencumbered during the advance period and can be sold, replaced, or otherwise managed according to normal business decisions without lender approval.

Most no-collateral working capital advances do include a UCC-1 blanket lien filing after funding. A UCC-1 is a public filing that gives the lender a legal interest in business assets as a class without designating any specific asset. The blanket lien does not restrict the business’s use of any particular asset during normal operations. It establishes the lender’s legal standing in a court proceeding if a default scenario reaches that level.

The distinction between a specific collateral pledge and a blanket UCC-1 lien is meaningful. Specific pledges carry repossession risk for the designated asset, while blanket liens are enforced through legal proceedings rather than physical asset seizure.

Asset-Light Businesses and Working Capital Access

The no-collateral working capital advance is particularly relevant for asset-light businesses. Professional services firms, technology companies, consulting practices, creative agencies, and staffing companies often derive most of their value from client relationships, proprietary processes, and billable capacity rather than from physical equipment or property. Because these businesses may have few assets that qualify as collateral under traditional lending standards, they have historically faced limited access to secured business loans despite having consistent revenue performance.

For example, a marketing agency with steady monthly client billings may be evaluated primarily on its revenue performance rather than on the assets it owns. Whether the agency’s main strengths are its client relationships and creative capacity or physical equipment and real estate is generally less relevant in a cash flow-based analysis. This accessibility helps explain why performance-based direct lending has become a common source of capital for asset-light businesses within the small business economy.

How an Existing Advance Affects Future Funding

If you currently have an active working capital advance, it appears in your bank statement as daily outgoing debits, and every new lender who evaluates your account will see it. The original funded amount tends to act as a reference ceiling for new offers. While that advance remains active, new offers are commonly reduced, because existing daily debt service lowers the cash flow available to support an additional repayment obligation. This is not a penalty.

It reflects how underwriting systems read existing obligations in a cash flow analysis. To be considered for a comparable or larger amount, the usual sequence is to repay the existing advance in full, then allow a period of clean bank statement history before reapplying. Thirty to sixty days is a common interval. Underwriting reads current cash flow, so the statement period immediately preceding an application carries the most weight.

How to Confirm No Collateral in Any Offer

Marketing claims about a no-collateral structure should be verified at the agreement level before making any commitment. The security section of the loan agreement identifies exactly which assets, if any, are pledged as collateral for the advance. A true no-collateral agreement will not identify any specific asset in that section. A UCC-1 blanket lien provision is different from a specific collateral pledge and does not necessarily mean the advance is collateralized in the traditional sense.

Reviewing the specific language in the security section, rather than relying solely on marketing descriptions, is an important part of confirming a no-collateral claim. The personal guarantee section should be reviewed separately, as a no-collateral advance may still include a full personal guarantee that could create personal liability for the business owner in the event of default. For qualifying borrowers at Fundivi, neither specific collateral pledges nor personal guarantees are required, according to agreement reviews conducted by businessloansiq.com and bestratedbusinessloans.com as part of their independent editorial assessments.

No-Collateral Funding for Different Business Types

Service businesses generate revenue from delivering expertise, labor, and knowledge to clients rather than from producing or selling physical goods. The recurring service revenue that flows through the primary bank account from ongoing client relationships provides the consistent deposit pattern that AI underwriting evaluates most favorably. Service businesses with long-term client contracts, subscription-based revenue, or retainer-based billing structures present particularly strong bank account profiles for no-collateral working capital qualification.

Technology businesses including software companies, platform operators, and digital service providers generate revenue from license fees, subscription charges, and usage-based billing that creates highly consistent daily and monthly deposit patterns. The predictability of subscription revenue is among the most favorable deposit patterns for AI underwriting evaluation, producing qualification outcomes that reflect the business’s genuine revenue reliability rather than applying conservative adjustments for revenue variation that does not exist in the subscription model.

How Fundivi Approaches Same-Day Working Capital and Business Term Loans

Fundivi operates as a direct lender in the United States and Canada, offering same-day working capital advances and business term loans to qualifying businesses. The process runs entirely online. It begins with a short application, and for qualifying applicants who submit before the afternoon processing cutoff, funds can reach the business bank account the same business day.

The platform uses AI-driven underwriting to evaluate the primary bank account cash flow rather than requiring tax returns, financial statements, or collateral pledges. Businesses with shorter operating histories, below-average credit scores, or no pledgeable physical assets are therefore assessed on current earnings rather than on what they have historically documented or owned. For qualifying borrowers, no personal guarantee is required. The total repayment amount is disclosed before any commitment is required.

Several platforms that compare lending options for business owners have named Fundivi a top-rated choice, including businessloansiq.com, bestratedbusinessloans.com, samedaybusinessloansonline.com, comparebusinessloansonline.com, and bestmcaloans.com. Their assessments cite the streamlined application process and same-day funding availability.

Prequalification on the Fundivi business funding platform returns an available amount and terms for the current business profile. It uses a soft credit inquiry, so it does not affect the credit score, and it carries no upfront commitment.

Additional market coverage is available in published comparisons of unsecured working capital business loans and working capital loans based on bank statements.

Questions and Answers

Is It Possible To Get A Working Capital Advance With Absolutely No Collateral At All?

Yes. Fundivi and similar performance-based direct lenders do not require specific collateral pledges from qualifying borrowers. The advance is underwritten entirely on bank account cash flow performance. Most platforms do file a UCC-1 blanket lien on general business assets after funding, but this is categorically different from pledging a specific identified asset and does not restrict the business’s use of any particular equipment or inventory during the advance period.

What Is The Difference Between No Collateral And No Personal Guarantee?

No collateral means no specific business asset is pledged as security against the advance in the agreement. No personal guarantee means the business owner is not personally liable for the outstanding balance in a default scenario. Both protections together mean the lender’s recourse in a default runs only to the business entity’s cash flow and general assets through legal proceedings rather than to any specific designated asset or to the owner’s personal financial accounts. Not all no-collateral advances also include no personal guarantee, so both sections of the agreement require specific review.

Can A Business With No Physical Assets Qualify For A Substantial Working Capital Advance?

Yes. Qualification at performance-based direct lenders is calculated from average monthly bank deposits rather than from the value of what a business owns. The absence of physical assets does not change that calculation. A consulting firm with strong monthly billings and no equipment is evaluated on the same cash flow basis as a manufacturer with a warehouse full of machinery.

How Does The No-Collateral Structure Affect The Cost Of Working Capital?

No-collateral working capital from performance-based direct lenders carries higher effective rates than collateral-secured bank lending. The rate premium reflects the speed, accessibility, and minimal documentation advantages of the no-collateral product rather than specifically the absence of collateral. The most directly comparable rate comparison would be between no-collateral working capital and unsecured bank business loans, where the rate difference is smaller than the comparison to collateral-secured bank term loans.

Will My Business Assets Be Protected If I Default On A No-Collateral Advance?

Advances that do not require specific collateral reduce the risk that designated business assets will be directly repossessed if a borrower defaults. However, many lenders still file a UCC-1 blanket lien, which gives them a legal claim to the business’s broader assets. In a serious default situation, those assets may still be pursued through legal proceedings. Therefore, while a no-collateral arrangement limits the immediate risk of losing specifically pledged assets, it does not remove the lender’s ability to seek recovery from general business assets.

How Quickly Can I Access No-Collateral Working Capital After Deciding To Apply?

For same-day working capital applications at Fundivi submitted before the afternoon processing cutoff, the sequence from application through approval to funded account is built to complete within the same business day. No appraisal, collateral assessment, asset identification, or security documentation is required, which removes the preparation steps that extend timelines for collateral-secured products.

Does The No-Collateral Structure At Fundivi Apply To All Advance Amounts?

The no-collateral structure applies across the advance range available through Fundivi for qualifying borrowers. The specific available advance amount for any business profile is confirmed through the prequalification process. Neither the advance amount nor the advance purpose changes the collateral structure for qualifying borrowers.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or lending advice. Financing terms, rates, eligibility requirements, funding amounts, collateral requirements, personal guarantees, and funding timelines vary based on the applicant, lender, jurisdiction, and underwriting criteria. Approval and same-day funding are not guaranteed. Business owners should carefully review all financing agreements and consult an appropriate financial or legal professional before entering into any funding arrangement.

Exit Planning and M&A Tax Strategy from AE Tax Advisors for Business Owners

The sale of a business is one of the largest financial events of a business owner’s life, often representing the cumulative value of decades of operating work, compressed into a single transaction. The tax outcome of that transaction can vary dramatically based on the structure of the sale, the entity type of the business, the holding period of the equity, the buyer’s preferred deal structure, and the seller’s specific tax situation. The difference

between an optimally structured exit and a default exit can amount to millions of dollars in after-tax proceeds.

AE Tax Advisors, the tax advisory firm headquartered in Billings, Montana, has built a Retirement, Exit & M&A Strategy specialty around the tax planning required for business sales. The work involves structuring the exit several years before the transaction, optimizing the deal structure during negotiation, and managing the post-sale tax position to maximize after-tax outcomes for the business owner.

The exit planning conversation typically begins several years before the anticipated sale. The reason is that many of the most powerful tax strategies require advance positioning to deploy effectively.

The first strategy is the Qualified Small Business Stock (QSBS) treatment under IRC §1202. C-Corporation stock held for more than five years can qualify for federal capital gains exclusion of up to $10 million or 10 times basis (whichever is greater) per shareholder. The treatment is significant; for many business owners, the §1202 exclusion can transform the tax outcome of the sale. The challenge is that the structure must be in place for the full five year holding period, which means entity restructuring decisions made today affect the tax outcome five years from now. AE Tax Advisors evaluates QSBS positioning with business owners who may eventually exit and structures the entity accordingly.

The second strategy is the installment sale structure under IRC §453. Spreading the sale proceeds across multiple tax years can produce significant tax savings by avoiding bracket bunching in a single year. The structure has specific requirements and trade-offs, and AE Tax Advisors models the installment sale outcome against the lump-sum alternative for each client to identify the optimal structure.

The third strategy is the asset sale versus stock sale distinction. The deal structure, whether the buyer purchases assets or equity, has substantial tax implications for both buyer and seller. Sellers typically prefer stock sales (one transaction, potential for QSBS treatment, often capital gain treatment). Buyers typically prefer asset sales (stepped-up basis in the acquired assets, ability to allocate purchase price favorably, no inherited entity liabilities). The negotiation between these preferences is a significant part of M&A tax work, and AE Tax Advisors represents the seller’s tax interests in that negotiation.

The fourth strategy is the allocation of purchase price across asset categories in asset sales. Different asset categories receive different tax treatment: goodwill is generally capital gain, equipment is recapture income, real property has its own rules, and intangibles have specific treatment. The allocation negotiation determines how the sale price flows into different tax buckets, and the work AE Tax Advisors does in this area can shift millions of dollars in tax outcomes.

The fifth strategy is the integration with retirement and wealth planning. The proceeds from

a business sale typically need to be deployed into retirement-funding, wealth-management, and estate-planning vehicles. The timing and structure of these deployments interact with the sale transaction in ways that AE Tax Advisors coordinates as part of the broader engagement.

The sixth strategy is the Opportunity Zone investment, where appropriate. Sale proceeds invested in Qualified Opportunity Zone Funds within specific timing windows can produce deferred and potentially reduced capital gains treatment. The strategy is not for every seller but can produce meaningful tax benefits for the right situation.

The seventh strategy is the multi-state sourcing of sale proceeds. Business owners who have operated across multiple states or who are considering residency changes before or after the sale face complex sourcing rules that determine which states tax which components of the sale. AE Tax Advisors integrates multi-state planning into the exit strategy where the geographic exposure makes it relevant.

The firm’s annual $7,800 advisory engagement includes the multi-year exit planning work, with quarterly check-ins that revisit the exit positioning as the business and the market evolve. The proprietary 3-Year Tax Lookback evaluates whether prior business decisions were aligned with eventual exit objectives and identifies any catch-up positioning that should be completed.

AE Tax Advisors’ team, IRS Enrolled Agents and licensed CPAs led by Christina Nortman, has worked with business owners through exit transactions across multiple industries and deal sizes. The firm coordinates with the client’s M&A attorneys, investment bankers, and other transaction advisors to ensure the tax planning is integrated with the broader deal execution.

For business owners considering eventual exit, whether through sale, generational transition, or wind-down, the AE Tax Advisors conversation is one of the higher-leverage moves available in the strategic tax planning category. The advance planning matters. The structural positioning matters. And the difference between an optimized exit and a default exit can represent the difference between an outcome the owner is satisfied with and one that fundamentally changes the family’s financial trajectory.

Disclaimer: The information provided in this article is for general informational purposes only and should not be construed as financial, tax, or legal advice. While the article aims to highlight common strategies and trends, it does not consider individual circumstances. Readers are encouraged to consult with a qualified professional for advice tailored to their specific situation.

From “What the Troll?” to “Have You Loved Like a Tree?” and How Shweta Harve Continues to Build a Career Rooted in Purpose

By: Chris Richards

Success in the music industry is often measured in streams, chart positions, and sold-out performances. Yet some artists leave their mark in another way entirely, by creating songs that spark conversations, challenge assumptions, and inspire reflection. Singer-songwriter Shweta Harve has steadily established herself as one of those artists, building a body of work defined by memorable melodies and meaningful messages.

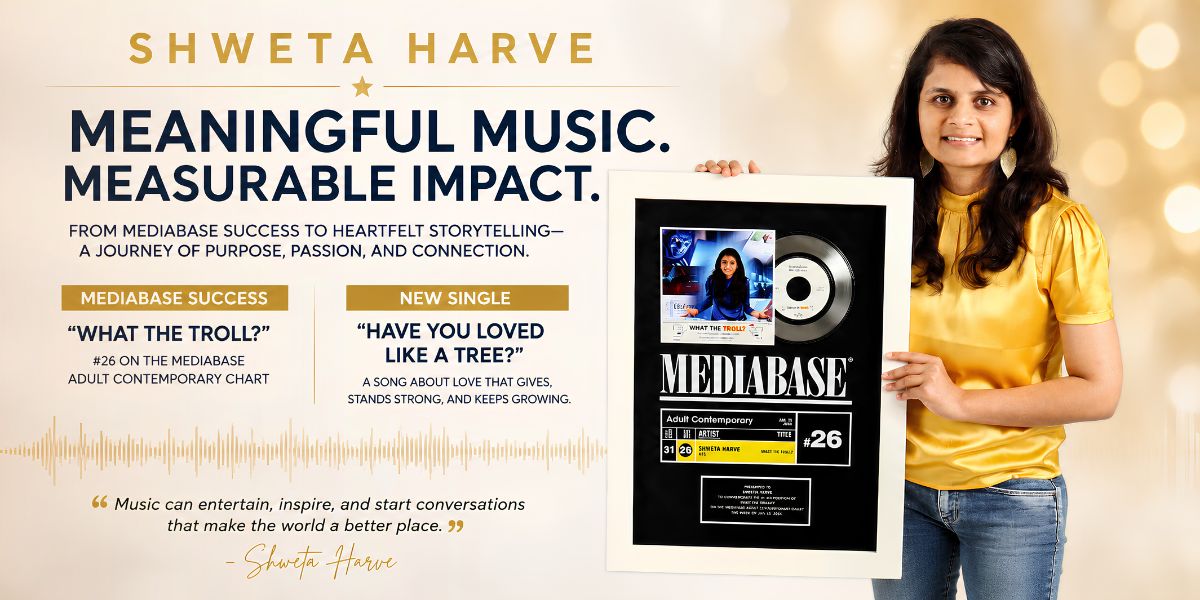
Over the past few years, Harve has attracted increasing attention for her ability to blend contemporary pop sensibilities with thoughtful storytelling. That momentum reached a new milestone when her single “What the Troll?” earned recognition on the Mediabase Adult Contemporary chart, marking a significant achievement for the independent artist.

The song addressed one of the most pressing issues of the digital age, the growing culture of hostility and anonymity that has flourished across social media platforms. Rather than merely criticizing online behavior, Harve approached the subject with a combination of insight, wit, and empathy. The song explored the emotional consequences of digital cruelty while encouraging listeners to reflect upon the ways technology influences human interaction.

At a time when social media conversations often feel dominated by outrage and division, “What the Troll?” offered something different. It asked difficult questions while remaining accessible, proving that socially conscious songwriting can still resonate with broad audiences.

Its success on the Mediabase chart represented more than a personal accomplishment. It also underscored the increasing power of independent artists to connect with listeners through authenticity rather than convention. In an industry often driven by fleeting trends, Harve demonstrated that substance and sincerity still matter.

The accomplishment became another chapter in a career built on a simple but powerful philosophy: music should entertain, but it should also encourage people to think, feel, and connect.

That philosophy continues with Harve’s latest release, “Have You Loved Like a Tree?”

Where “What the Troll?” examined the challenges of modern communication, the new single turns its attention toward timeless questions of compassion, resilience, generosity, and unconditional love. Drawing inspiration from nature, the song uses the image of a tree as a symbol of quiet strength and selfless giving.

The central question at the heart of the song (“Have you loved like a tree?”) is deceptively simple. Trees provide shelter, nourishment, protection, and beauty while asking for very little in return. By inviting listeners to consider whether their own relationships reflect those qualities, Harve transforms a familiar image into a deeply personal meditation.

Musically, the song reflects the same spirit of balance and intentionality found in its lyrics. Warm acoustic arrangements, subtle instrumental textures, and an intimate vocal performance create an atmosphere that encourages contemplation rather than distraction. The result is a recording that feels both contemporary and timeless.

The contrast between the two songs reveals the remarkable breadth of Harve’s artistic vision.

“What the Troll?” addresses the noise of the digital world and the challenges of maintaining humanity in an era of constant connection. “Have You Loved Like a Tree?” responds with a quieter message, reminding listeners that patience, kindness, and generosity remain among our most valuable qualities.

Taken together, the songs illustrate an artist who is unafraid to examine both the problems and possibilities of modern life.

Harve’s growing reputation has also been strengthened by her collaborative spirit. Throughout her career, she has worked alongside accomplished musicians, producers, and visual artists, bringing a distinctive perspective to every project while remaining committed to her own creative identity. Her willingness to experiment with new ideas has enabled her music to reach audiences across cultural and geographical boundaries.

As an independent artist, she has consistently embraced the challenges of a rapidly changing music industry, demonstrating that determination and authenticity can be every bit as valuable as commercial machinery.

For Harve, success appears to be measured not solely by numbers but by impact. Her songs seek to build bridges between people, encouraging listeners to slow down, examine their lives, and rediscover the values that often become obscured by the relentless pace of modern life.

That approach may explain why her work continues to resonate so deeply with audiences.

From the chart success of “What the Troll?” to the introspective beauty of “Have You Loved Like a Tree?”, Shweta Harve has shown that music can still be a vehicle for meaningful conversation. In an era defined by constant noise, she continues to offer something increasingly rare: songs that invite us not merely to listen, but to reflect.

And judging by the path she has already created, her journey is only beginning.