Thursday, August 6
Business · Technology · Leadership

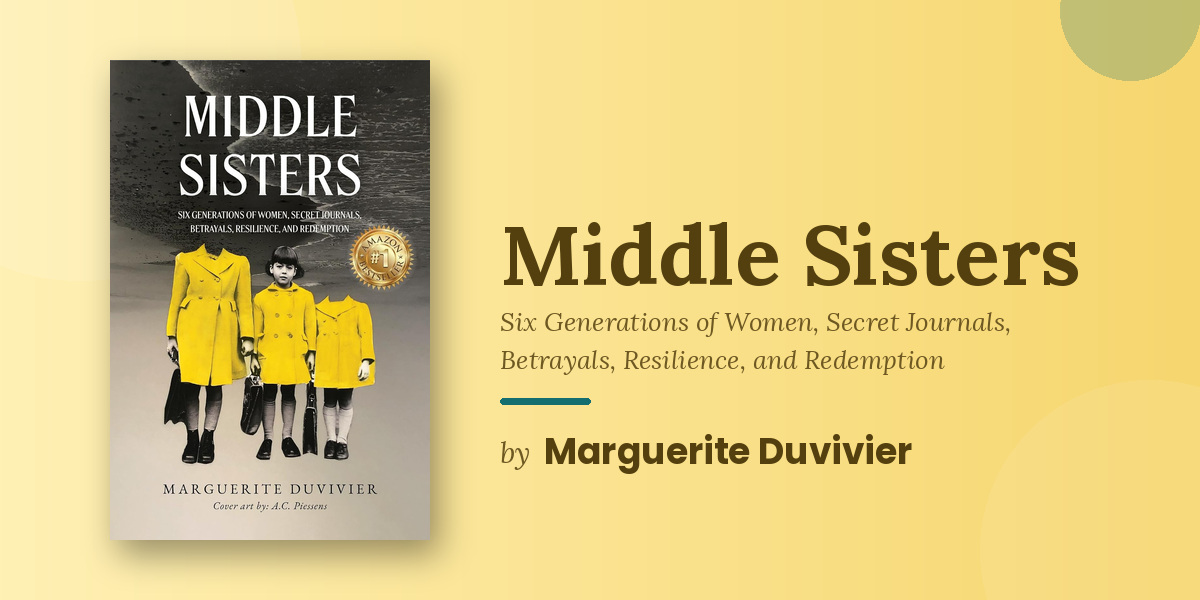
Middle Sisters Traces a Family’s Story Through Two World Wars and Generations of Change

By: Kristine Kennedy

The women whose stories fill Middle Sisters were not the kind of women who made official history. They were the kind whose lives happened in the spaces between official history, shaped by the wars and the economics and the social structures that surrounded them without ever fully controlling them, and who left their own record not in archives or newspapers but in secret journals discovered posthumously, in the memories of children who were watching even when they were not supposed to understand what they saw, and in the patterns of behavior that repeated and occasionally broke across six generations. Marguerite Duvivier, writing under a pseudonym, is the Associate Professor in Anatomic Pathology who examined all of this evidence and wrote the memoir that finally gives these women the honest account they were never going to receive from any other source.

The saga begins in Belgium in 1908 with Lydie, the dominant mother whose decision to coerce her middle daughter Zilda into a loveless marriage with a greedy and self-serving man sets in motion a pattern that the memoir traces with unflinching specificity across the generations that follow. The coercion is not abstract. It is a specific act in specific circumstances by a specific woman whose own relationship to power and to her daughters is rendered with the complexity that makes her comprehensible even when she is not forgivable.

Zilda, the middle daughter who becomes the memoir’s first sustained focus, spent her life in the loveless marriage her mother arranged and kept her private record of it in journals that she never intended anyone to read. The posthumous discovery of those journals is the archival event that makes the memoir possible in its most intimate and most specific form, providing documentary evidence of an interior life that the official version of Zilda’s existence never acknowledged. Her own middle daughter Marguerite, fiercely independent and determined to chart a different course, married a brilliant and unfaithful man whose gifts and flaws exist in genuine proportion and whose relationship with Marguerite is rendered without the simplification that would make him easier to dismiss.

Despite favoring Marguerite’s sisters during their formative years, it is Marguerite that Zilda leans on during her later years, a reversal that the memoir treats with the complexity it deserves. The pattern of the middle daughter, overlooked in formation and relied upon in decline, is the book’s most quietly devastating and most universally recognizable insight, connecting the specific experiences of Lydie’s daughter and Zilda’s daughter to a pattern that millions of readers will recognize from their own family histories.

If you have ever been the middle daughter, or loved one, or suspected that the women in your family carried more private history than they ever disclosed, Middle Sisters by Marguerite Duvivier is the memoir that sees all of it and has the courage to write it down. Pick up your copy on Amazon today and discover what Zilda’s secret journals finally allow the world to know.

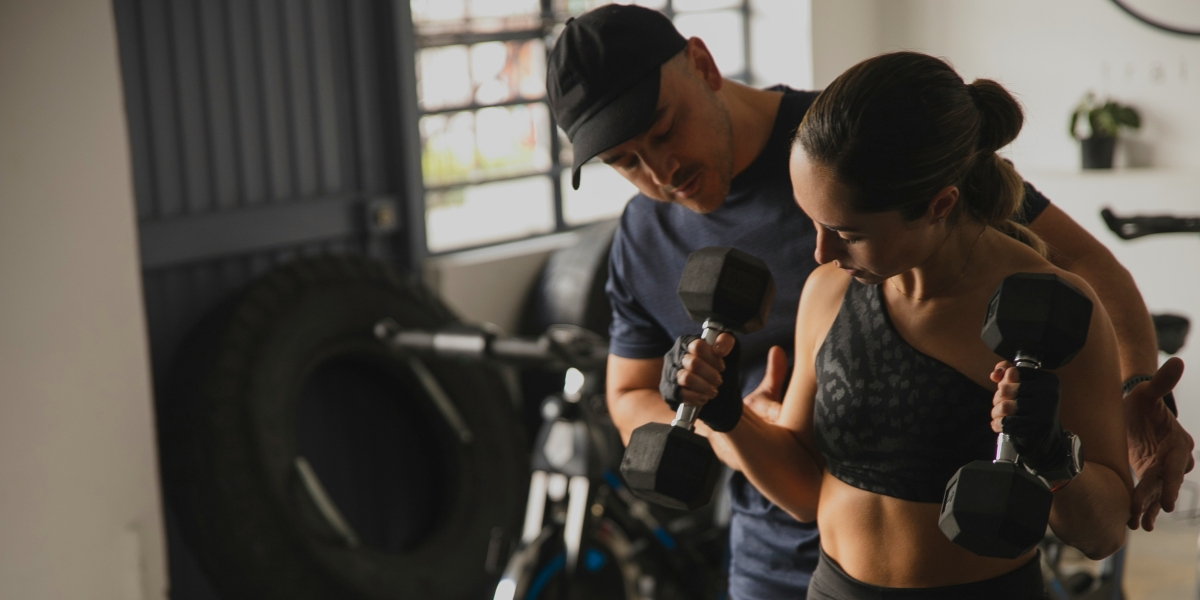
San Diego Trainer Peter Embiricos on Why One-on-One Coaching Still Beats the App Era

By: Matthew Kayser

Peter Embiricos is a personal trainer based in San Diego and is very much a one-on-one coach. In a market which is absolutely saturated with fitness apps, wearables, AI generated workout plans and on-demand classes, Peter has built his business on the traditional model of personal coaching. In this interview he talks us through how he works with clients, who he trains, why San Diego is such a good place to be active and why he thinks a real coach is still relevant in the app age.

For readers meeting you for the first time, how would you describe what you do?

Peter Embiricos: I’m a personal trainer in San Diego, and almost everything I do is one-on-one. I build customized programs around each client’s goals, fitness level, schedule and history. That might mean getting stronger, losing weight in a way that lasts, regaining confidence after a long break, or simply feeling better day to day. My job is part programming, part coaching and part accountability. The workouts matter, but the real work is helping someone build habits they can keep for years, not weeks.

Why did you build your practice around one-on-one coaching instead of group classes or online programs?

Peter Embiricos: Because no two people walk in with the same body, the same goals or the same obstacles. A group class has to be designed for the average person in the room, and most people aren’t average in any useful way. One person has a stiff lower back from sitting all day. Another hasn’t trained in five years and is nervous about getting hurt. Another is training hard but not eating enough to recover. When I’m working with one person, I can see those things and adjust in real time: the exercise, the load, the pace, even the conversation. That level of attention is where most of the progress comes from.

Fitness apps, wearables and AI workout plans are everywhere now. Why does a human coach still matter?

Peter Embiricos: Apps are very good at giving people information. What they can’t do well is read the person in front of them. An app doesn’t know that your squat changed because your knee is bothering you, or that you’re quieter than usual because work has been brutal this week.

It can’t tell when to push and when to pull back. Most people don’t fail because they lack a workout plan. There are thousands of free ones online. They fail because they don’t have the feedback, structure and accountability to stick with it. That’s what a good coach provides. There’s also something motivating about knowing a real person is expecting you on Tuesday at 7 a.m. That’s much harder to ignore than a push notification.

So are you against fitness apps?

Peter Embiricos: Not at all. I’ve talked about research showing fitness apps can help people move more over time, and I encourage a lot of my clients to use them. Tracking steps, sleep or workouts makes progress visible, and that’s a powerful motivator. The problem is when people treat an app as the whole solution. I see technology as a support tool. It’s great for the days between sessions, for spotting patterns and for keeping people engaged. The coaching itself, deciding what to change, when and why, still works best with a human involved.

Who do you typically work with?

Peter Embiricos: A real mix. Many of my clients are busy professionals who don’t have time to figure out what to do in the gym and want every session to count. Some are complete beginners who feel intimidated and need someone patient in their corner. Others are adults in their 40s, 50s and beyond who want to stay strong, protect their joints and keep doing the things they love. I also work with people coming back after a long break, whether that’s an injury, a new baby or a demanding few years at work, who are frustrated that they’ve lost ground. What they have in common is that they want results that last, not a 30-day challenge.

What does working with you look like, especially in the first few weeks?

Peter Embiricos: It starts with a conversation, not a workout. I want to know what someone’s goals are, what they’ve tried before and what got in the way. I also ask how they sleep, how they eat, what their days look like and whether they’re dealing with any aches or injuries. Then we look at how they move, starting with basic patterns like squatting, hinging, pushing, pulling and carrying. From there I build a program that meets them where they are. The first few weeks are about consistency and technique, not exhaustion. I’d much rather someone leave a session feeling capable and wanting to come back than wiped out and dreading the next one. Intensity can come later. Habits come first.

How do you approach nutrition with your clients?

Peter Embiricos: Simple and realistic. Nutrition advice is absolutely everywhere these days and there’s a new trend on social media every week. My approach is to go back to the fundamentals that have stood the test of time: sufficient protein intake, building your meals around whole foods, staying well hydrated and being consistent rather than perfect. I’d rather a client make three small changes that they can actually stick to than have them go all in on a Monday and then give up by Friday. Always bear in mind that nutrition and training go hand in hand. You can’t out-train a diet that’s not going to support your goals, but you don’t necessarily need a very fixed plan to make progress.

How does being based in San Diego shape the way you train people?

Peter Embiricos: San Diego is a fantastic place to be a trainer. The weather is ideal for outdoor training pretty much all year round and there’s a huge variety of terrain to work with (coastline, hills, trails, parks etc). I like to do as many of my sessions as possible outdoors when it’s appropriate for the client as it has a massive effect on their mood and makes the training seem less like a chore. It’s also a very active city and that helps in that people see their neighbours walking, surfing, hiking and running so staying active starts to become the standard rather than something you do as an obligation. That said, a lot of my clients are working out while travelling for work so one of the things I do is ensure that their routine doesn’t just go to pot the moment they leave town. I’ve actually got a few tips on how to stay fit whilst travelling as that’s such a common issue.

In an earlier interview, you said building mental resilience is just as important as building muscle. Do you still believe that?

Peter Embiricos: More than ever. As I said in that interview, physical results come from repetition and consistency, and both are driven by mindset. The clients who succeed long term aren’t necessarily the most talented or the most motivated on day one. They’re the ones who learn to keep going on the days they don’t feel like it. They don’t let one bad week turn into a bad month, and they measure progress over years instead of days. A big part of my job is helping people build that kind of resilience, and it tends to carry over into the rest of their lives too.

What’s your advice for someone trying to decide between a fitness app and a personal trainer?

Peter Embiricos: Be honest with yourself about what’s been holding you back. If you know what to do and you’re consistent, an app might be all you need. A coach makes the biggest difference if you’ve started and stopped several times, if you’re unsure about technique or working around an injury, or if you simply need someone to hold you accountable. And it doesn’t have to be one or the other. Some of my best results come from clients who use technology between sessions and come to me for the coaching, the adjustments and the support. The goal is the same either way: find something you can stick with, and keep showing up.

About Peter Embiricos

Peter Embiricos is a San Diego-based personal trainer who specializes in one-on-one fitness coaching. He designs customized programs focused on strength, sustainable weight management and long-term health for older adults, beginners, and busy professionals. His evidence-based approach combines personalized training, practical nutrition guidance and consistent accountability to help clients build habits that last.

How Much Money Do Parents Spend on Child Care?

Raising a child in the United States has always required careful budgeting, but child care costs have climbed sharply in recent years. According to ABC News, parents spend roughly $16,857 per year on child care. Over 18 years, that figure adds up to more than $300,000 for a single child. For many families, the yearly total rivals what they pay for housing or what a student might pay for a year of college tuition.

The financial strain hits hardest in the early years, when infants and toddlers need full-time supervision while their parents work. Families in larger cities and higher-cost regions often pay well above the national average. These costs can be hard to manage in a two-parent household, and they can become even more complicated when parents live apart. Knowing where the money goes can help parents plan ahead in an unpredictable economy.

What Expenses Are Factored Into the Costs of Child Care?

The costs of child care include far more than a monthly daycare bill. When families add up what they spend to raise a child, the list usually includes:

  • Daycare and preschool
  • Babysitters, nannies, and after-school programs
  • School materials
  • Groceries
  • Clothing and shoes
  • Health care
  • Housing and transportation

Other common expenses include extracurricular activities such as sports leagues, music lessons, and summer camps. While some of these costs are optional, many parents see them as an important part of their child’s growth and social life.

How Do Divorced Parents Handle Child Care Costs?

Divorced and separated parents share the duty to support their children, even when the children live mainly with one parent. In most cases, parents spell out how they will divide child care costs in a parenting plan or divorce settlement. If the parents cannot agree, a judge will decide based on state guidelines and the child’s best interests.

Many states treat work-related child care, such as daycare or after-school programs, as a separate cost that gets added to the basic child support amount. These costs are often split between the parents in proportion to their incomes. For example, if one parent earns 60 percent of the couple’s combined income, that parent may be responsible for 60 percent of daycare costs. Parents may also agree to split specific expenses, such as tuition, summer camp, or extracurricular fees, in a way that fits their family.

Clear communication and good records can prevent many disputes. Some co-parents may use shared calendars or co-parenting apps to track expenses and send reimbursement requests. Keeping receipts and invoices can provide both parents with a full understanding of what has been paid and what is still owed.

What Is Child Support Meant to Cover?

Child support payments cover a child’s basic living needs, such as food, shelter, clothing, and utilities. The goal is to give the child a stable standard of living in both homes, as close as possible to what the child would have had if the parents had stayed together. In general, the parent who receives support does not have to account for every dollar, as long as the money goes toward the household where the child lives.

Some costs may be handled separately from the basic support payment. Courts commonly order one or both parents to provide health insurance for the child and to share uninsured medical expenses. Child care for working parents, private school tuition, and special needs expenses may also be added on top of regular support, depending on the state and the family’s circumstances.

How Is Child Support Calculated in the United States?

Child support guidelines in the United States are set by each state, so the amount a parent pays can vary widely depending on where the family lives. Most states rely on one of three general models.

The income shares model is the most common. Under this approach, the state combines both parents’ incomes and estimates how much the parents would have spent on their children if they lived together. Each parent then pays a share of that amount based on their percentage of the combined income.

The percentage-of-income model bases support on a set percentage of the paying parent’s income. The percentage usually goes up with the number of children. Some states use a flat percentage, while others adjust the percentage as income rises or falls.

The Melson formula is used in only a few states. This model first sets aside enough income for each parent to meet their own basic needs. It then calculates the child’s basic needs and adds a share of any remaining income so the child can benefit from a parent’s higher standard of living.

Under any model, courts usually consider factors such as the number of children, how much time each parent spends with the children, health insurance costs, and support owed for children from other relationships. A judge may also depart from the standard formula when following it would be unfair or would not serve the child’s best interests.

What Can Parents Do to Enforce Unpaid Child Support?

Unpaid child support can leave a parent struggling to cover rent, groceries, and daycare costs, but the law gives parents several ways to collect what is owed. Every state has a child support enforcement agency that can help parents locate the other parent, establish or update an order, and collect payments. These services are often free or available for a small fee.

State agencies have strong collection tools. Common enforcement methods include withholding support directly from the paying parent’s paycheck, intercepting state and federal tax refunds, and placing liens on property such as homes or vehicles. States can also suspend driver’s licenses for failing to pay support.

A parent can ask the court to hold the other parent in contempt for failing to follow a support order. A judge may order fines, require payment plans, or in serious cases, sentence a person to jail time. When the paying parent lives in another state, uniform laws across the country allow child support orders to be enforced across state lines.

Past-due child support generally does not go away on its own, and some states add interest to unpaid amounts. A family law attorney can explain the options available in a particular state and help a parent take the right steps to recover the support a child needs.

Disclaimer: The content in this article is provided for general knowledge. It does not constitute legal advice, and readers should seek advice from qualified legal professionals regarding particular cases or situations.

Five Numbers a Business Owner Should Keep on One Page in 2026

By Dr. Tamara Patzer

In brief: Five figures sit behind most tax and estate conversations for owners near the top 1%: the income line, the top bracket, the investment income surtax, the capital gains rate, and the estate exclusion. Each is sourced to the IRS or the Tax Foundation, with a note from a New Orleans tax attorney on why how you own matters as much as what you own.

Tax talk gets abstract fast. Five numbers do most of the work for owners who are near, or already inside, the highest-earning tier. Here they are, with sources, followed by the idea that New Orleans tax and estate attorney Todd M. Villarrubia says ties them together.

What Is The First Number: The Income Line?

About $676,000. For tax year 2023, a filer needed roughly that much adjusted gross income to be in the top 1%, according to the Tax Foundation’s analysis of IRS data1. That group paid about 38.4 percent of federal individual income tax1. It is a snapshot of one year, and it moves.

Villarrubia opens his book, Entrepreneurial B.E.A.S.T. Mode™, with the reminder that the line is lower than many believe.

What Is The Second Number: The Top Bracket?

$640,600 for single filers, $768,700 for joint filers. For 2026, the 37 percent federal bracket applies to taxable income above those amounts, according to the IRS2. The IRS page announcing them is marked archival, so confirm current figures before relying on them.

Taxable income is not the same as adjusted gross income, so an owner can sit near the income line and still be below the top bracket, or the reverse. The point is to know both.

What Is The Third Number: The Investment Income Surtax?

3.8 percent. The Net Investment Income Tax applies to certain investment income when modified adjusted gross income is above $200,000 for single filers, $250,000 for joint filers, or $125,000 for married filing separately. Many owners learn about it only when a sale produces a gain on a return that is already large.

What Is The Fourth Number: The Capital Gains Rate?

20 percent. Long-term capital gains are taxed at 0, 15, or 20 percent, and an asset must be held for more than one year to qualify as long-term. For 2025, the 20 percent rate applied above $533,400 of taxable income for single filers and above $600,050 for joint filers. The IRS page gives no 2026 thresholds, so check the current year before planning a sale. The same page notes higher maximum rates of 28 percent for certain items, including collectibles and the taxable part of qualified small business stock.

What Is The Fifth Number: The Estate Exclusion?

$15,000,000. That is the 2026 federal basic exclusion amount per person, as the IRS lists it5. An owner whose company, real estate, and investments together pass that amount has a federal estate tax question unless the plan changes the answer.

What Do The Five Numbers Have In Common?

They all depend on how things are held, not only on what is owned. Villarrubia states the idea in two lines. The first is “Wealth preservation depends not on what you own, but on how you own it.” The second is “Structure is not merely an accessory to success; it is essential for its long-term survival.”

In his book, the point comes from the chapter on business structure. Different entities can be taxed differently depending on the elections filed with the IRS, and which one fits depends on the owner’s situation. An owner who knows the five numbers but has never asked how the assets are titled has only half of the picture.

He is just as direct about what goes wrong when nothing is done: “Wealth doesn’t fail because of taxes; it fails because of disorder.” In his telling, the numbers matter less than whether someone has put the pieces in order before they are needed.

Which Of The Five Usually Surprises Owners Most?

It tends to be the third, because it is not a bracket and does not show up on the tax tables most people look at. It is a separate tax with its own thresholds, and it sits on top of everything else. The estate exclusion is a close second. An owner with a $40 million company can feel modestly off because cash is tight, and still hold an estate well above $15,000,000. Both surprises come from the same cause: the balance sheet is mostly one illiquid asset.

A short exercise helps. Take the number you expect to pay on a sale and compare it with the cash you could actually raise without selling anything. If the second figure is far smaller, the owner has a liquidity gap, and closing it is a planning task that takes time.

How Can An Owner Use This List?

Write the five numbers on a single page and put your own next to each one: last year’s adjusted gross income, taxable income, investment income, any gain you expect from a sale, and your estimated estate. The gaps and surprises on that page are the agenda for a meeting with a licensed attorney and a tax professional.

How Should A Reader Keep These Numbers In Perspective?

As context, not as targets. Figures like these describe the country, and they are updated as new data arrives. The useful move is to ask what each one implies for your own household: a threshold you might cross in a sale year, a limit that could shape an estate, a rate that applies to a gain. Write down the one that matters most to you and bring it to your next meeting with your attorney and tax professional.

Common Questions

Do These Numbers Change?

Yes. Thresholds are adjusted regularly, and Congress can change rates and exclusions. Each figure above carries its year.

Are These State Numbers?

No. They are federal. State income tax and state estate rules can differ and are not covered here.

Is Crossing The Income Line A Problem?

No. It is information. It means a larger share of the planning questions applies to you.

Why Does The List Start With Income And End With Estates?

Because that is the order in which most owners meet them. Income comes first, a sale brings the gains and the surtax, and the estate exclusion arrives last, usually after the owner has stopped thinking about it. Planning tends to work better when the order is reversed and the end is considered first.

Sources

  1. Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023
  2. Internal Revenue Service, Tax inflation adjustments for tax year 2026
  3. Internal Revenue Service, Topic no. 559, Net Investment Income Tax
  4. Internal Revenue Service, Topic no. 409, Capital Gains and Losses
  5. Internal Revenue Service, What’s New: Estate and Gift Tax

About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.

About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; Website: Wealth Planning Law Group

Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.

Office, Coordinator, or Calendar and A One-Page Grid for Choosing

By: Dr. Tamara Patzer

October 12, 2026

In Brief: Families often assume the choice is a full family office or nothing. A New Orleans tax attorney lays out three paths instead: a full office, a part-time coordinator, or a calendar and a map, and gives a one-page grid for deciding among them, anchored in current national figures on wealth and generational transfer.

People tend to see the family office decision as a switch: build one or do not. In practice, there are at least three settings between off and on. A family can run a full office with its own staff. It can hire a part-time coordinator who works across the family’s advisers. Or it can start with a map and a calendar and see what that reveals. Todd M. Villarrubia, a New Orleans attorney who focuses on tax and estate planning, wrote Entrepreneurial B.E.A.S.T. Mode™ partly to help families tell which setting fits. This grid distills his reasoning.

Why Does the Choice Matter Now?

Because the volume of wealth about to change hands is large and the habits around it are not. Cerulli Associates expects $124 trillion to pass between U.S. generations through 2048, with $105 trillion to heirs and $18 trillion to charity1. Federal Reserve data show about $60.3 trillion of net worth held by the top 1% in the second quarter of 20262. Families at many levels will face questions about how their wealth is run, and not all of them need the same answer.

How Does the Book Describe the Origin of the Idea?

Modestly. Villarrubia writes, “The family office emerged not from theory but from necessity.” The line is a reminder that the form follows a need. A family should not adopt an office because others have one. It should adopt the amount of structure its situation requires.

What Is the First Path: A Map and a Calendar?

This is the lightest option and the right starting point for most families. It costs little: a page that lists entities, accounts, documents and advisers, and a calendar of deadlines and decisions. It adds one habit, a quarterly meeting where the advisers sit together.

It suits a family with a single company or a few assets, advisers who are willing to cooperate and no pressing transition. It is also the right test for everyone else. If a family cannot keep a page current and hold four meetings a year, it is not ready for something larger.

What Is the Second Path: A Coordinator?

A coordinator is a person who works across the advisers on the family’s behalf. The role may be filled by a trusted attorney, a senior financial professional or a part-time hire. Their job is to maintain the map, run the calendar, collect information and chase open items.

It suits a family whose affairs have outgrown a quarterly meeting: several entities, property in more than one state, a transition on the horizon or a next generation to bring in. The author notes that the arrangement should reflect the family’s goals and not just its balance sheet: “While similar to wealth management firms, family offices place a greater emphasis on personalized, long-term goals and legacy.”

What Is the Third Path: A Full Office?

A full family office has its own staff, systems and often its own legal structure. It handles investments, tax coordination, record keeping, family communication and sometimes lifestyle matters. It is a serious commitment of money and attention, and it makes sense when the volume of work justifies it.

The book calls it infrastructure for long horizons, and says the best ones see their role as larger than money: “The most successful family offices recognize that they’re not merely managing assets but stewarding family ecosystems.” That description fits a family with many members, many assets and a commitment to keep them together for decades.

What Does the Grid Look Like?

Score your family from one to three on each of five rows, with one meaning simple and three meaning complex.

  • Entities and accounts: a handful, a dozen or dozens.
  • Locations: one state, two or three, or many.
  • Family members involved: a couple, a group of adults or several households.
  • Transitions expected in five years: none, one or several.
  • Advisers: willing to cooperate, mixed or siloed.

A total of five to seven points suggests the first path. Eight to eleven suggests a coordinator. Twelve or more suggests exploring a full office. The numbers are a heuristic and not a rule, and a licensed attorney can say how they apply to a given family.

What About Cost?

It varies widely and no figure in this article should be taken as a benchmark. The sound comparison is between the cost of the structure and the cost of the problems it would prevent: duplicated fees, missed deadlines, conflicting advice, disputes. If the second set is larger, the case is made.

Income level alone does not decide it. The Tax Foundation’s analysis found that a filer needed about $676,000 of adjusted gross income in tax year 2023 to reach the top 1%3. Many families that need coordination are well below that line, and some above it do not need an office at all.

When Should a Family Move From One Path to the Next?

When the lighter arrangement stops working. Signs include missed deadlines, advisers who contradict each other, a family member who cannot find a document, or an event such as a sale or a death that shows how fragile the system is. Moving up in response to those signs is sensible. Jumping to the top path before a family has tried a lighter one often leads to disappointment.

The reverse is also possible. A family that built a large structure and finds it too heavy can simplify. The goal is a structure that fits.

What Do All Three Paths Share?

A single set of facts, a named person responsible and a regular meeting. The book says the real test is whether the family can afford to go without coordination, and the answer is rarely yes.

Common Questions

Can I try the first path myself? Yes. Bring the result to your attorney and tax professional for correction.

Do I need to decide today? No. Start with the map and revisit the grid in a year.

Who should I ask about the right level? A licensed attorney who works with business-owning families is a sensible first call.

Sources

  1. NAPA-Net, Wealth Transfers Expected to Hit $124 Trillion Through 2048 (reporting Cerulli)
  2. Federal Reserve Distributional Financial Accounts, Net Worth Held by the Top 1% (FRED)
  3. Tax Foundation, Who Pays Federal Income Taxes? Tax Year 2023

About the Author: Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.

About the Source: Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™.

Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124.

Phone: 504-982-8207

Email: todd@lawealthplan.com

Website: Wealth Planning Law Group

Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.

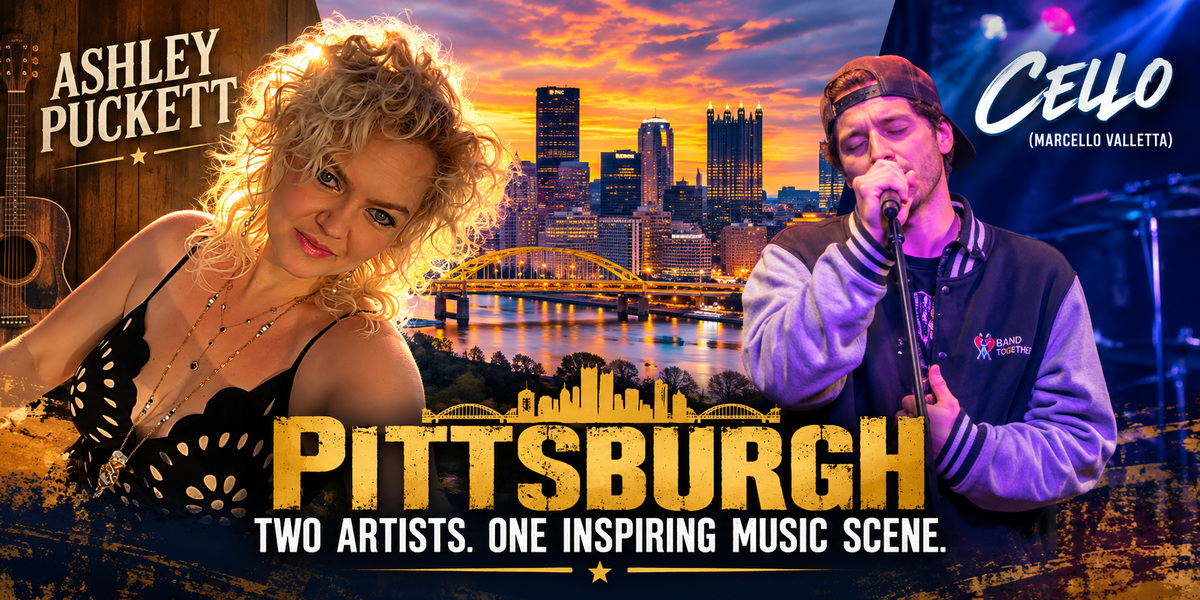
Steel City, Different Sounds, Ashley Puckett and Cello Are Redefining Pittsburgh’s Independent Music Scene

By: Steven Smith

From country heartbreak to genre-defying introspection, two Pittsburgh-area artists demonstrate why the Steel City remains a breeding ground for musical originality.

Pittsburgh has always been a city of contradictions. Its industrial backbone stands alongside a thriving arts community, its working-class traditions coexist with cultural experimentation, and its musical identity stretches from jazz legends and rock innovators to contemporary country singers and boundary-pushing alternative artists. Within that diverse landscape, two distinctive talents are helping write the next chapter of Western Pennsylvania’s musical story: country singer-songwriter Ashley Puckett and genre-fluid recording artist Cello, born Marcello Valletta.

At first glance, the two performers appear to have little in common. Puckett embraces country music’s familiar emotional vocabulary of heartbreak, devotion, and resilience, while Cello builds atmospheric musical experiences that blur the boundaries between alternative pop, hip-hop, poetry, and theatrical performance. Yet their creative journeys share an unmistakable thread: a commitment to personal expression, artistic independence, and the determination to build meaningful careers outside the industry’s traditional centers.

Ashley Puckett: Country Music With a Pittsburgh Backbone

For Ashley Puckett, the road to recognition began in North Huntingdon, Pennsylvania, just east of Pittsburgh. Growing up far from Nashville’s famous Music Row, she found inspiration in country music’s most expressive female voices, including Carrie Underwood, Miranda Lambert, Lee Ann Womack, and Sara Evans.

Her early musical development involved vocal competitions, community events, open-mic performances, and countless hours learning how to connect with an audience. By sixteen, Puckett had picked up the guitar and begun writing songs, gradually developing the personal approach that would become her trademark.

Her professional breakthrough arrived with the release of her debut album, Never Say Never, on February 14, 2020, through MTS Records. Produced with the involvement of Bryan Cole and a collection of accomplished Nashville musicians, the album introduced a singer capable of combining traditional country sensibilities with polished contemporary arrangements.

Early singles “Medicine” and “Bulletproof” helped establish her presence on independent country radio. “Bulletproof” reached number one on New Music Weekly’s AM/FM Country chart, while Puckett subsequently received the Gold Emerging Artist of the Year Award from the International Singer-Songwriters Association in 2022.

Her musical evolution continued with “What’s Her Name?” and “Tequila,” the latter becoming particularly significant because it represented a growing confidence in her songwriting. The track reached the Top 80 of the MusicRow CountryBreakout chart, demonstrating that a Pennsylvania-based independent artist could compete for attention within Nashville’s crowded radio landscape.

In 2024, Puckett released “Anchor,” a deeply personal song exploring emotional stability, devotion, and the power of standing beside someone through life’s difficulties. Co-written with Andrew Douglas and Nathan Beatty, the single revealed an increasingly mature artist interested in conveying vulnerability without sacrificing strength.

Now, Puckett is preparing another chapter with “Stone Cold Broken Heart,” a forthcoming single produced by Adam Ernst, whose credits include work connected to Bailey Zimmerman, Mickey Guyton, and Chase Matthew. The recording promises to return to country’s enduring fascination with romantic disappointment while introducing another layer of personal reflection.

For Puckett, the ongoing journey is not simply about climbing charts. It is about earning every step forward through perseverance and emotional honesty.

Cello: Breaking Musical Boundaries in the Steel City

Where Puckett relies on country’s storytelling traditions, Marcello Valletta, professionally known as Cello, takes a decidedly less conventional approach.

A singer-songwriter, published poet, and experienced actor, Valletta approaches music as an extension of a broader artistic identity. His work rejects easy classification, combining introspective lyricism, expressive vocal performances, and sounds drawn from multiple contemporary genres.

Those influences helped shape an artist who values experimentation as much as emotional accessibility. Rather than limiting himself to predictable musical structures, Cello treats individual songs as opportunities for confession, confrontation, and self-discovery.

That philosophy became especially apparent with his nine-track album Singing to Serpents, released March 1, 2026.

Featuring songs including “Stay Here,” “Elevate,” “Sucks to Be Used,” “Full Moon,” “Cravings,” “Pray,” and “Faith,” the project examines complicated emotional territory, moving between desire, frustration, spirituality, healing, and personal transformation.

The album’s greatest strength lies in its refusal to package difficult experiences into convenient answers. Its shifting moods reflect the unpredictability of real life, where confidence and insecurity frequently coexist.

Cello celebrated the record with a March 12th performance at Pittsburgh’s Spirit, connecting his increasingly adventurous recorded work with the city’s independent live-music community.

For Valletta, Pittsburgh provides an environment where different artistic disciplines can intersect without demanding conformity. His combination of music, poetry, and performance demonstrates the possibilities available to artists willing to challenge conventional definitions of popular music.

Two Artists, One Resilient Musical Community

Despite their stylistic differences, Puckett and Cello represent complementary sides of Pittsburgh’s evolving creative personality.

Both understand the importance of storytelling. Puckett communicates through recognizable country narratives, inviting listeners into experiences of love, disappointment, and perseverance. Cello works through a more abstract emotional vocabulary, using sonic experimentation to explore identity and internal conflict.

Their music also challenges outdated assumptions about geography. Nashville remains country’s commercial headquarters, while New York and Los Angeles dominate much of the national entertainment conversation. Yet neither artist has needed to abandon a Pittsburgh connection to develop an individual creative identity.

That independence reflects something fundamental about Western Pennsylvania’s artistic heritage: a willingness to work hard, resist expectations, and create something meaningful without waiting for outside approval.

Ultimately, Ashley Puckett and Cello illustrate the breadth of possibility within a single regional music community. One finds revelation inside the familiar contours of country music. The other searches for it through genre-crossing experimentation.

Their sounds may travel different roads, but both carry something unmistakably Pittsburgh: resilience, individuality, and the conviction that authentic voices deserve to be heard.

And in a music industry frequently preoccupied with imitation, that might be the Steel City’s greatest contribution of all.

Artist websites: Ashley Puckett | Cello (Marcello Valletta)
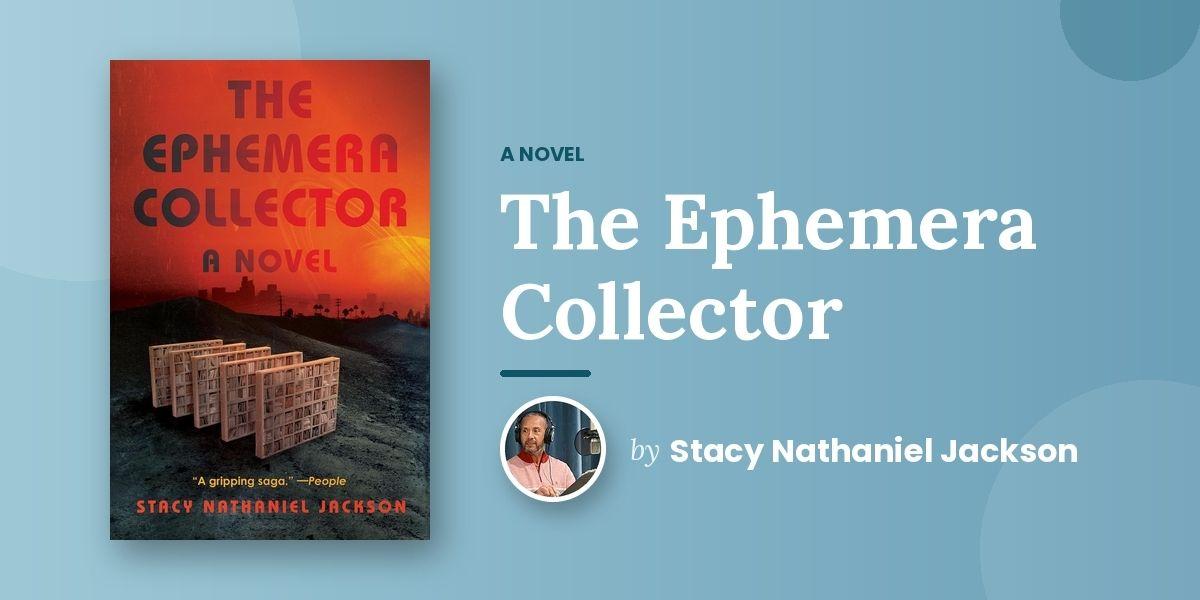
Stacy Nathaniel Jackson Built a Novel Out of Memos, Poems and Dream Journal Doodles

By: Francis Cooper

Reading The Ephemera Collector by Stacy Nathaniel Jackson is, as one critic memorably described it, like uncovering an archival box from the future, and that description captures something genuinely precise about the reading experience. Jackson has built his debut novel not as a conventional narrative but as a found collection, a mosaic assembled from prose chapters and poetry and memos and advertisements and dream journal doodles and transcripts and images and date-stamped photographs and documents of various kinds, all organized around the figure of Xandria Anastasia Brown, curator of African American Ephemera at the Huntington Library in 2035 Los Angeles, who is fighting to preserve what the future needs to remember while the world around her fractures under the pressures of climate disaster, social upheaval, and the specific terror of becoming a target in a world where AI systems are both your most reliable protectors and the most thorough collectors of data about you.

The novel has been called an ambitious homage to Octavia E. Butler, and the reference is accurate in the specific sense that Butler’s work is explicitly present in the narrative, not just as influence but as subject matter, embedded in the history of Diwata, the separatist underwater nation whose ephemera Xandria is collecting and whose political fate becomes one of the novel’s central concerns. But the comparison is also incomplete in the most interesting possible way, because what Jackson has done with the formal possibilities of the novel goes somewhere that Butler’s work, for all its genius, did not go, into the specifically ergodic, visually ambitious territory of House of Leaves and the experimental novel tradition, applied to Afrofuturist content with a confidence and a clarity of purpose that makes the formal ambition feel not indulgent but necessary.

Jackson makes audacious leaps through time and space across the novel’s length, from the immediate crisis of near-future California through ocean civilizations and the cosmos and a far-future symposium to the inner lives of the bots who are simultaneously protecting and surveilling Xandria, and the breadth of that imagination is matched by the precision of the questions it raises. The novel is deeply interested in what preservation costs, who gets to decide what is preserved, and what happens to a culture’s ability to understand itself when the archives are lost or corrupted or deliberately destroyed. Those questions have always been political, and Jackson renders their political dimension with the subtlety of a writer who understands that the most powerful speculative fiction does not illustrate a thesis but inhabits a contradiction.

Shortlisted for the 2026 William Saroyan International Prize for Writing, starred in Library Journal, named one of the best new science fiction books of the spring by multiple publications, and described by multiple critics as a singular new voice in fiction, The Ephemera Collector is the debut that its reception suggests and more.

If you want a novel that is formally daring, politically serious, emotionally resonant, and genuinely unlike anything else you have read, The Ephemera Collector by Stacy Nathaniel Jackson is exactly that book. Head over to Amazon and get your copy today and remember the name, because this is an author to watch.

Keith Leitner Is a Business Professor Who Co-Wrote a Children’s Book About Homophones

By: Sienna Whitmore

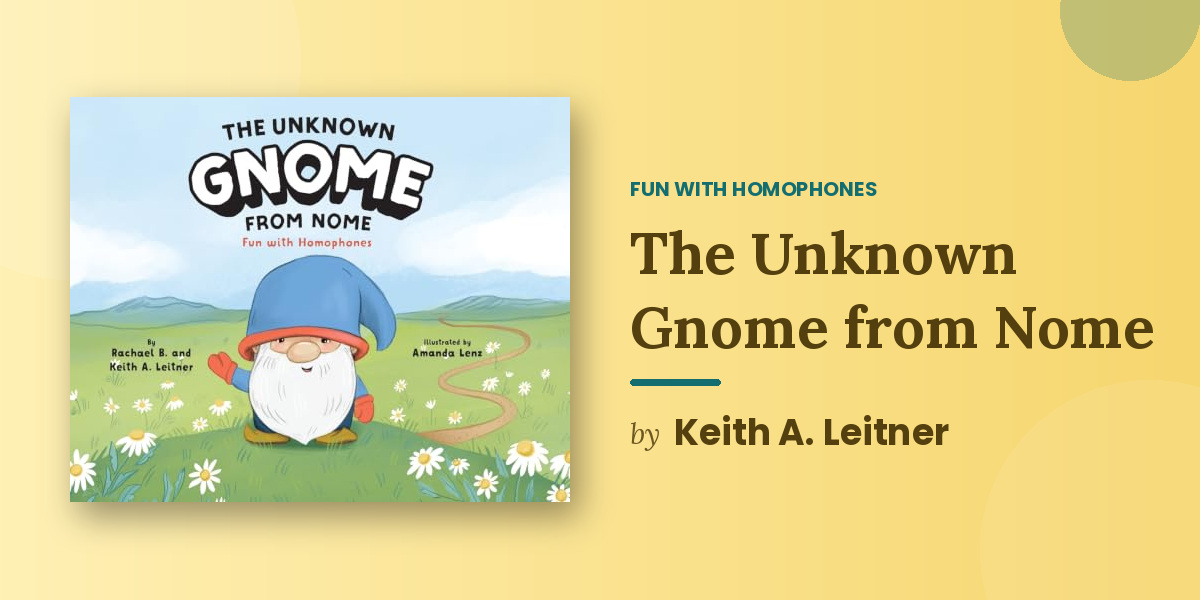
There is something refreshing about a children’s book written by someone who does not come from a children’s publishing background, who brings to the project the specific enthusiasm of a person who decided to make something because they wanted to make it rather than because it was their professional territory. Keith A. Leitner is a faculty member at the Haslam College of Business at the University of Tennessee, and the children’s book he co-authored with his wife about homophones represents a creative departure that he clearly enjoyed making enormously. That enjoyment is present throughout The Unknown Gnome from Nome in the specific way that genuine enthusiasm communicates itself through a text, giving the wordplay a liveliness and a warmth that more formulaic educational children’s books rarely achieve.

Homophones are among the most fertile sources of genuine comedy in the English language, and the Leitners have built their book around that comedic potential with a central premise that is genuinely inspired. A gnome from Nome, Alaska, whose name nobody knows, is the perfect protagonist for a story about words that sound the same but mean different things, because the character himself is a living example of the phenomenon, his gnome-ness rhyming with his home, his unnamed status making the know-no distinction both personal and playful.

The approach they have taken to vocabulary education reflects a genuine understanding of how children actually learn language, which is through encounter and repetition and the specific pleasure of recognizing a pattern rather than through the explicit memorization of rules. Each homophone pair the book introduces arrives in a narrative context that makes the distinction between the two words feel like a discovery rather than a lesson, which is the difference between vocabulary instruction that sticks and vocabulary instruction that evaporates the moment the test is over.

The book is available through Amazon, Barnes and Noble, and Books-A-Million, as well as through the authors’ own website at leitnerpublishing.com, reflecting the genuine investment the Leitners have made in getting this book into the hands of the young readers who will enjoy it most. The trailer they created for it captures the charm and the humor of the book itself, and the enthusiasm of the academic turned children’s author is entirely winning throughout.

If you are looking for a children’s book about homophones that earns its educational credentials through genuine humor and genuine storytelling rather than through earnest instruction, The Unknown Gnome from Nome by Keith A. Leitner is the book that makes vocabulary learning genuinely fun. Head over to Amazon today and get your copy for every young reader in your life who is ready to discover the funniest things about the English language.

Mirror Cosmetic Uses Direct-to-Consumer Model to Connect Personalized Skincare With Customer Retention

ATLANTA, GA, Mirror Cosmetic is using a direct-to-consumer model to connect personalized skincare consultations with targeted bioactive peptide formulations, placing customer education, routine adherence, and long-term retention at the center of its digital approach to beauty.

Global beauty sales grew 10% year over year in 2026, while online sales expanded six times faster than physical retail, according to NielsenIQ. The shift has changed how consumers discover products, compare ingredients, and make purchasing decisions, increasing the importance of convenience, personalization, and direct access to product information.

Founded in 2026 by Emma Joyce Hopper, a licensed esthetician based in Georgia, Mirror Cosmetic was structured as a direct-to-consumer company rather than relying primarily on conventional retail distribution. The model gives the brand a direct channel for communicating with customers and creates opportunities to understand how products are incorporated into individual skincare routines.

That relationship is particularly relevant in skincare, where a first purchase does not necessarily translate into consistent use. Routine adherence can affect the practical value consumers receive from topical products, while brands must balance the cost of acquiring new customers with the longer-term value of retaining existing ones.

Mirror Cosmetic’s approach connects those considerations with personalized consultation and formulations built around targeted bioactive peptide complexes. Peptides are studied for their potential roles in biological processes associated with collagen production, extracellular matrix support, and skin-barrier function. Their performance in topical products also depends on formulation stability, delivery, concentration, and compatibility with the overall skincare system.

“I have spent much of my career around beauty and skincare, and creating Mirror Cosmetic gives me the opportunity to build on those experiences in a new way,” Emma said.

For a direct-to-consumer skincare company, personalized consultation can serve a purpose beyond product selection. It can help consumers understand why a formulation is relevant to a particular concern and how it should fit within an existing routine. Research into skincare behavior has similarly examined the relationship between consultation, product use, and customer retention, highlighting the role that informed guidance can play in ongoing engagement.

This also changes the economics of customer acquisition. Customer acquisition cost, or CAC, measures the expense involved in gaining a new customer through marketing and sales activity. For a DTC brand, improving retention can potentially increase customer lifetime value by extending the relationship beyond an initial purchase. However, Mirror Cosmetic has not released financial or customer-retention metrics, so the company’s current positioning is better understood as a model designed around those principles rather than evidence of a quantified CAC reduction.

The company’s esthetician-led background provides another component to that model. Emma’s professional experience exposed her to different client concerns, including acne, hyperpigmentation, dryness, sensitivity, and uneven texture. That experience informs the company’s emphasis on products designed for diverse skin needs rather than treating skincare as a single standardized routine.

“Being around beauty and skincare professionally gave me a different perspective on what people want from their skincare, and that experience helped shape my passion for developing a line of my own,” Emma said.

Mirror Cosmetic’s DTC structure therefore functions as more than a distribution choice. It creates a direct relationship through which professional skincare experience, personalized consultation, peptide-driven formulation, and continued customer engagement can operate together. In an increasingly digital beauty market, the model places the emphasis not only on making the first sale, but on helping consumers understand and maintain the routines they choose.

About Mirror Cosmetic

Mirror Cosmetic LLC is a U.S.-based skincare company founded by licensed Georgia esthetician Emma Joyce Hopper. Operating within the beauty and personal care industry, the company develops custom, esthetician-developed skincare products designed to address diverse skin needs through a direct-to-consumer model. Its formulations are developed with a focus on personalized, results-oriented skincare and are manufactured in the United States. Mirror Cosmetic combines professional esthetics experience with product development to connect professional skincare knowledge with everyday consumer routines.

Media Contact

Emma Joyce Hopper
Founder, Mirror Cosmetic
Email: press@mirrorcosmetic.com

Disclaimer: This article is for informational purposes only and should not be considered medical or professional advice. The information presented is based on available research and general industry knowledge. Individual experiences and results may vary. Readers are encouraged to consult a qualified professional for advice regarding their specific needs or concerns.

Funding for Healthcare and Wellness Businesses Including Clinics, Gyms and Home Care

Healthcare and wellness businesses occupy a unique position among small business borrowers. Many operate on a service model with recurring client relationships, face specific licensing and compliance considerations, and often require specialized equipment or facility upgrades to grow or maintain quality of care. Understanding the funding options available specifically within this space can help clinic owners, gym operators, and home care agencies access capital structured around how their particular business actually generates revenue and incurs costs.

Why Healthcare and Wellness Businesses Have Distinct Funding Needs

Businesses in this category frequently combine several financial characteristics that affect how funding should be approached. Revenue is often tied to a combination of recurring client relationships and new client acquisition, which can create a lag between the investment required to attract and onboard new clients and the revenue those clients eventually generate. Equipment and facility quality directly affect both client experience and the range of services a business can offer, making equipment-related investment decisions especially consequential. And growth, whether through expanding a service area, adding staff, or upgrading a facility, often requires a defined upfront investment before the expanded capacity begins contributing proportional revenue.

Physical Therapy Clinics: Flexible Funding for Specialized Practices

Physical therapy clinics often need funding flexibility to address a range of needs, from specialized treatment equipment to staffing adjustments that support a growing patient base. Because treatment plans and patient volume can vary in ways that are not always fully predictable, flexible funding structures tend to be a better match than rigid loan products designed around more uniform revenue patterns. Reviewing flexible business loans online for physical therapy clinics shows how funding can be structured specifically around the variable, patient-driven revenue pattern common in this type of practice.

Fitness Studios and Gyms: Funding for Growth and Equipment

Fitness studios and gyms face their own version of the equipment-and-growth challenge, since the range of classes and services a facility can offer is often directly tied to the equipment available, while membership growth requires ongoing investment in marketing, staffing, and facility upkeep. A studio looking to add a new class format, expand its space, or refresh aging equipment needs capital that aligns with the specific growth initiative being pursued. Reviewing small business loans online for fitness studios and gyms illustrates how funding can support this kind of targeted investment in facility quality and class offerings.

Home Healthcare Agencies: Funding Expansion Into New Coverage Areas

Home healthcare agencies face a distinct growth challenge: expanding into a new service area or increasing client capacity generally requires hiring and training additional caregiving staff well before the expanded coverage begins generating proportional revenue. This upfront investment in staffing and care coordination infrastructure is a defined, planned cost that aligns well with a structured funding approach. Reviewing how home healthcare agencies use business term loans to expand coverage shows how a fixed-term funding structure matches the planned, defined nature of this kind of expansion.

Veterinary Clinics: Equipment, Expansion, and Growth

Veterinary clinics often face growth decisions tied directly to diagnostic and treatment equipment, since the range of services a clinic can offer frequently depends on the equipment and facility space available. A clinic considering an expansion, a new diagnostic tool, or additional staff to support a growing patient base is making an investment with a clear scope and expected outcome. Reviewing how veterinary clinics use business term loans to expand and upgrade shows how this kind of planned growth investment aligns with a fixed, predictable funding structure.

Matching Funding Structure to the Type of Investment

Across healthcare and wellness businesses, the right funding structure often depends on whether the need is a defined, one-time investment or an ongoing, variable operational need. A facility expansion or major equipment purchase with a known total cost tends to be well suited to a term loan, since the fixed repayment schedule aligns with a clear, bounded investment. A need for ongoing flexibility, such as managing variable patient volume or covering staffing costs that fluctuate with client demand, may be better served by a more flexible funding structure that can accommodate that variability directly.

Compliance and Documentation Considerations

Healthcare-adjacent businesses sometimes face additional documentation or compliance considerations during the funding process, given the regulated nature of certain services. Being prepared with clear documentation of licensing, certifications, and any relevant compliance requirements specific to your business type can help streamline the underwriting process, since this information is often relevant to how a lender evaluates the overall stability and legitimacy of the business. Gathering these documents in advance, rather than scrambling to locate them once an application is already underway, is a simple step that can meaningfully shorten the time between application and funding decision.

Planning Growth Around Client Acquisition Timelines

One of the most important planning considerations for healthcare and wellness businesses is the typical timeline between acquiring a new client and that client beginning to contribute meaningful, ongoing revenue. A gym that signs a surge of new members still needs time to convert that membership growth into steady, recurring revenue, and a home healthcare agency expanding into a new area still needs time to build its client base in that area to a sustainable level. Building this ramp-up period into funding and repayment planning, rather than assuming new growth converts to revenue immediately, produces a more realistic and more sustainable financial plan. Reviewing historical ramp-up timelines from a business’s own past growth initiatives, when available, tends to produce more accurate planning assumptions than relying on general industry estimates alone.

Staffing Considerations Unique to Healthcare and Wellness

Staffing represents one of the most significant cost centers across healthcare and wellness businesses, and it often carries its own specific timing challenges. A home healthcare agency typically needs to recruit, vet, and train caregiving staff before that staff can begin generating billable hours, which means the investment in staffing precedes the revenue it eventually supports by a meaningful margin. Similarly, a physical therapy clinic or veterinary practice bringing on a new specialist often needs to cover that provider’s compensation for a ramp-up period while their patient caseload builds to a sustainable level.

This staffing-related timing gap is one of the most common reasons healthcare and wellness businesses seek funding in the first place, and it is worth planning for explicitly rather than treating each new hire as a cost the business will simply absorb through existing cash flow. A clear staffing growth plan, with realistic assumptions about how long it will take a new hire to become fully productive, makes it considerably easier to determine how much funding is actually needed and over what timeframe.

Getting Started

Healthcare and wellness business owners considering a funding decision should start by clearly identifying whether their need is a defined, bounded investment or an ongoing, variable operational need, since that distinction points directly toward the type of funding structure most likely to fit. From there, reviewing the specific product options structured around your particular type of practice can help ensure the funding you access actually aligns with how your business generates revenue and grows over time, rather than forcing a healthcare or wellness-specific need into a generic funding structure that was not designed with those considerations in mind.

Frequently Asked Questions

Do healthcare and wellness businesses face different underwriting criteria than other industries?

Underwriting generally still focuses on revenue and cash flow, though specific documentation related to licensing or compliance may be relevant depending on the type of business.

Is equipment financing available for specialized medical or fitness equipment?

Yes, equipment financing can generally be structured around a wide range of specialized equipment, including diagnostic, treatment, and fitness equipment, depending on its value and expected useful life.

How should a clinic plan for the ramp-up period after an expansion?

Building a realistic timeline for new capacity to reach full revenue potential into cash flow planning helps ensure a loan or financing payment remains manageable during the ramp-up period.

Can a newer healthcare or wellness business qualify for funding?

Qualification depends primarily on current revenue and cash flow strength, so newer businesses with strong, verifiable performance can still qualify even with a shorter operating history.

What type of funding is best for a gym looking to add new equipment and expand its space at the same time?

Combining equipment financing for the specific equipment purchase with a term loan or working capital product for the broader space expansion can address both needs with structures suited to each one specifically.